No credit check broadband in the UK: what search actually runs, and what it leaves behind
Almost every broadband order runs a hard credit search, the providers say so themselves, and the search is recorded whether or not you are accepted. So the question worth asking is not who will let you in, it is what order to do things in so that fewer searches happen at all. Experian's own list of what triggers a hard check includes “You apply to a utility company”. TalkTalk is blunter still: “As part of our standard business policy, we always carry out a full credit check on all TalkTalk orders.” And Virgin Media publishes the sentence that matters most here: “The agencies will record details of the search, whether or not the application goes ahead.” So a refusal costs you the mark as well as the broadband, and the way to protect your file is to make one application rather than three. Two routes leave nothing behind. Smarty explains the first in one line: “We believe anyone should be entitled to mobile with no credit check. Because you pay upfront, we don't need to know your credit history.” The second is moving within a company you already pay, and BT publishes both halves of it: “If you're an existing BT customer switching to Home Essentials, we won't carry out a credit check.” Before either, read your own file, which is a soft search nobody else can see and which is free at all three agencies. Check your own file first, because looking at it yourself leaves no mark, and then make one application rather than three.
Start with your postcode
Which providers reach the address decides how much choice you have, and choice is what lets you apply once to the right one instead of working down a list and collecting a mark for each try.
Want to know what will be searched before you order? Answer three questions and see what each route leaves on your file. Been told a credit report costs £2? It is free, and here is the subsection that says so.
The short version, if you are worried about being refused
Direct answer: Almost every broadband order runs a hard credit search, the providers say so themselves, and the search is recorded whether or not you are accepted. So the question worth asking is not who will let you in, it is what order to do things in so that fewer searches happen at all.
Almost every guide to this subject, including the version of this one we have just replaced, is organised around finding a lenient provider. It sorts the market into who checks hard and who checks softly, and it tells you to aim at the soft end. The trouble is that the sorting is not based on anything the providers publish, and where they do publish something it usually says the opposite.
So this page is organised around the mechanism instead. There are four different checks, only one of them touches your credit file in a way anybody else can see, and knowing which is which turns a worrying decision into an ordinary one.
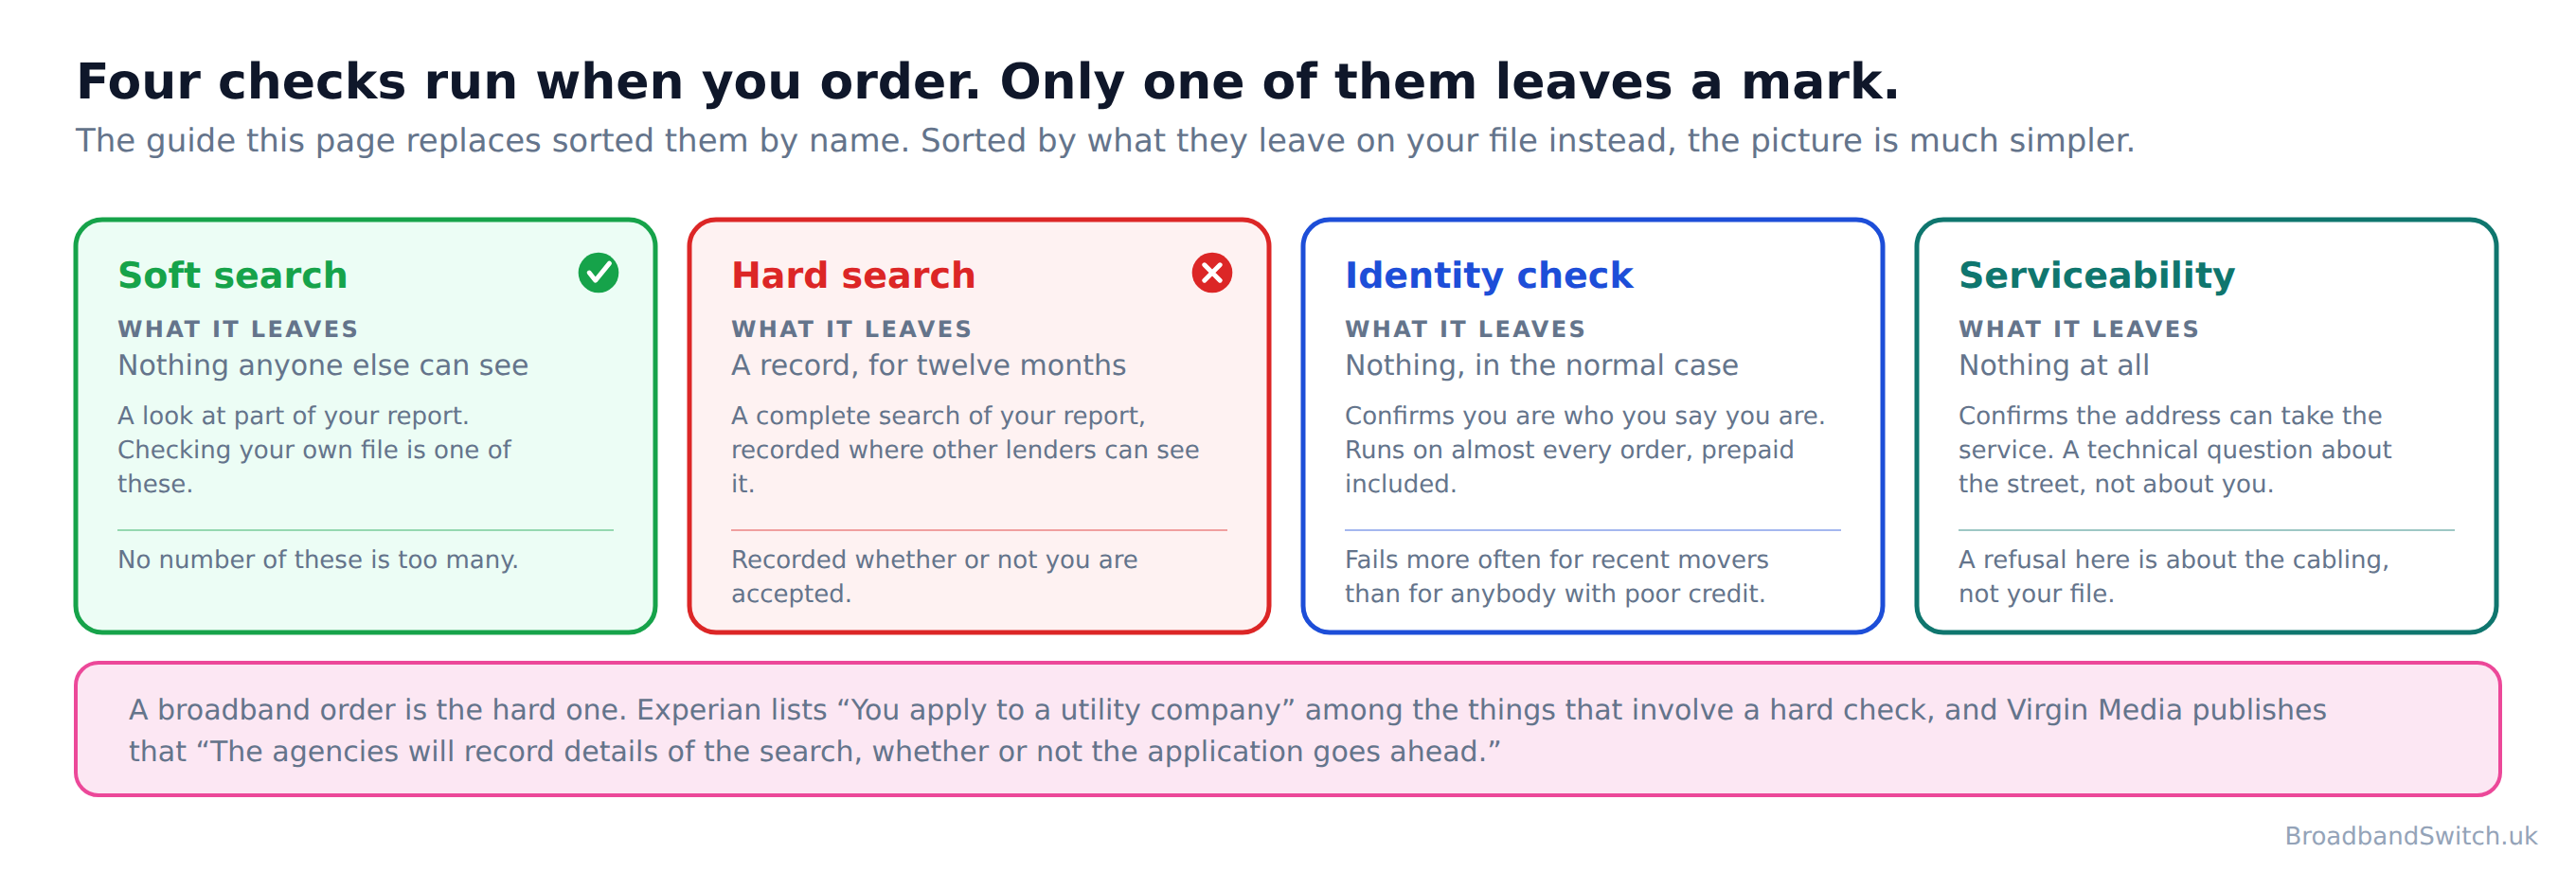
Sorting them that way makes the practical advice fall out on its own, and it is not the advice most guides give. It is not go to the lenient one. It is decide which provider you actually want before you apply to anybody, apply once, and arrive at that application having already done the two free things below.
Before any of them comes the step that costs nothing. Reading your own file is a soft search, and Experian publishes that “Soft searches aren't visible to companies”, so “they have no impact on your credit score or any future credit applications”. It is free at all three agencies, it takes about twenty minutes, and it tells you what the provider is about to see. Check your own file first, because looking at it yourself leaves no mark, and then make one application rather than three.
If the real problem is paying a bill you already have rather than getting a new connection, this is the wrong page and there is a better one: our guide to struggling to pay your broadband bill covers payment plans, arrears and the free debt charities properly. And if you qualify on benefits, our UK social tariffs guide is where the eligibility and the prices live.
Read your own file first, for nothing
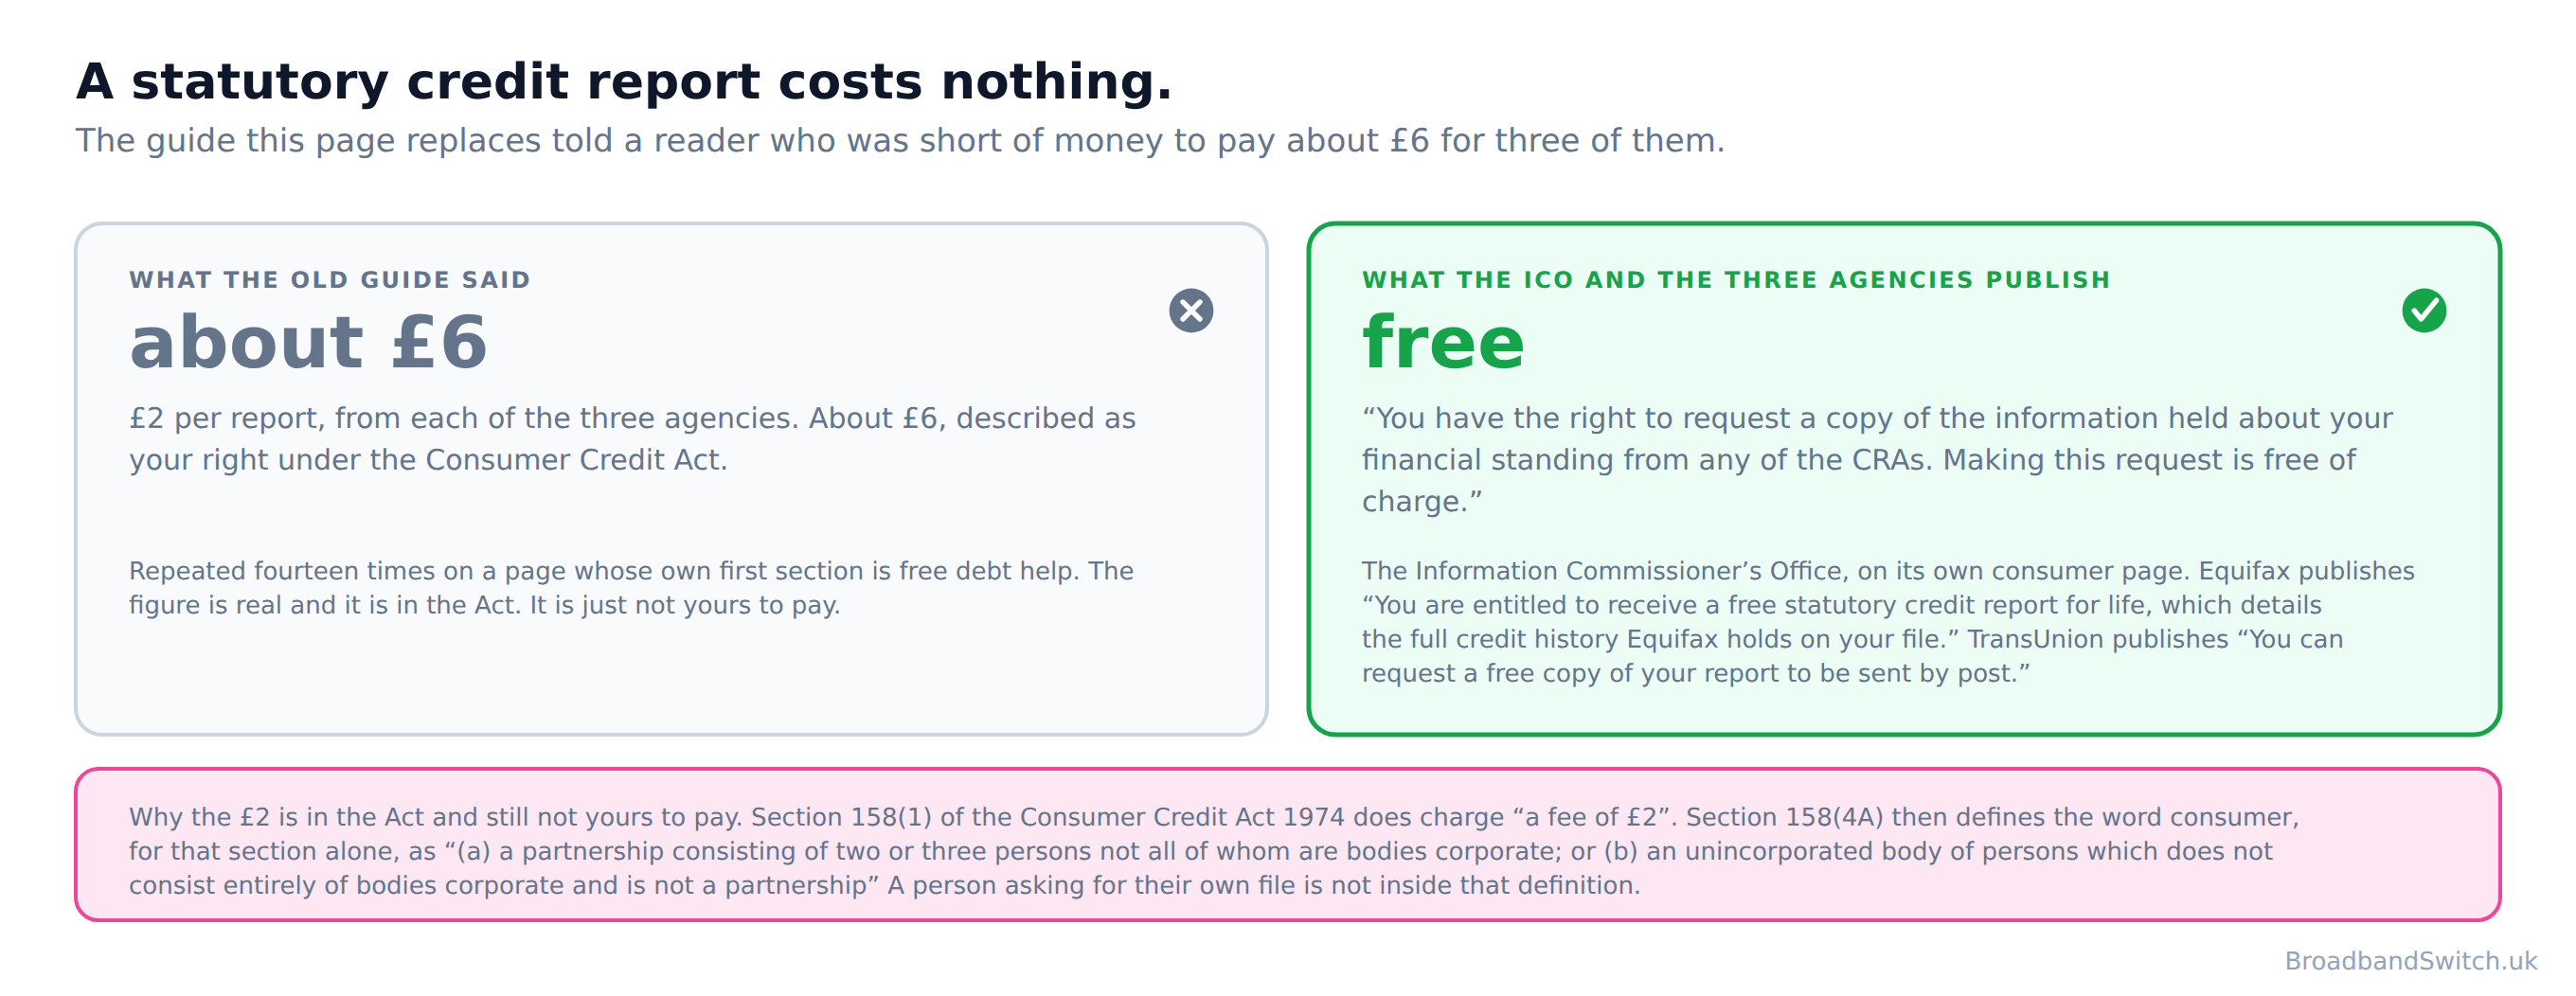
Direct answer: You have the right to request a copy of the information held about your financial standing from any of the CRAs. Making this request is free of charge.
That is the Information Commissioner's Office, on its own consumer page, and it is the first correction this page makes to its own previous version. The guide we replaced told a reader who was short of money to pay about £6 for something they are entitled to have for nothing, and it repeated the figure fourteen times.
The ICO also gives you the phrase to search for, which is the practical half: “If you want to request information about your financial standing, look for the phrase 'statutory report' on the CRAs' websites. You don't need to pay a fee for obtaining a statutory report.” Two of the three agencies say the same thing in their own words. Equifax: “You are entitled to receive a free statutory credit report for life, which details the full credit history Equifax holds on your file.” TransUnion: “You can request a free copy of your report to be sent by post.”
Why the £2 exists, and why it is not yours to pay
The fee every guide cites is real and it is in the legislation. Section 158(1) of the Consumer Credit Act 1974 requires an agency to supply a copy of the file to anybody who sends a written request, the particulars needed to find it, and “a fee of £2”. Stop reading there and £2 a report looks like settled law, which is exactly what happened to the page we replaced.
Subsection (4A) of the same section is the part nobody quotes: “(a) a partnership consisting of two or three persons not all of whom are bodies corporate; or (b) an unincorporated body of persons which does not consist entirely of bodies corporate and is not a partnership”. The £2 in the Act is real and it is not yours to pay. Section 158 defines the word consumer, for that section alone, as a small partnership or an unincorporated body, so an individual asking for their own file falls outside the fee entirely. A partnership of two or three people might pay it. You will not.
None of which matters much in practice, because the free routes are better anyway: a statutory report is the full file rather than a score, and you can have one from each of the three agencies. Experian, Equifax and TransUnion do not hold identical data, so a lender using one may see something a lender using another does not.
Looking costs you nothing, and there is no limit
Looking at your own credit file is a soft search and leaves nothing another company can see. There is no number of times that is too many. The fear of checking is common and it is the wrong way round: the search you can see on your own report is the one nobody else can. “A hard credit check happens when a company makes a complete search of your credit report. Each hard check is recorded on your report.” That is a different thing entirely, and it only happens when a company you have applied to asks.
Four checks, and only one leaves a mark
Direct answer: A soft search, a hard search, an identity check and a serviceability check all run at different moments and mean different things.
Understanding which is which is most of the value on this page, because three of the four are harmless and the fourth is the one worth planning around. The page we replaced listed five check types and sorted them by name, which is a reasonable way to write a table and not much help when you are deciding what to do.
The soft search
Experian's words, in two halves: “Soft searches aren't visible to companies”, and “they have no impact on your credit score or any future credit applications”. It is a look at part of your report rather than all of it, and the record it leaves is visible only to you. Every time you read your own file that is what happens, and eligibility checkers work the same way.
The hard search
“A hard credit check happens when a company makes a complete search of your credit report. Each hard check is recorded on your report.” This is the one that matters. Experian publishes three situations that involve one: “You apply for a loan, credit card or mortgage”, “You apply to a utility company” and “You apply for a pay-monthly mobile phone contract”. A broadband order is the middle one.
It does not last forever. “Most hard searches will stay on your credit report for 12 months.” EE says the same from its own side of the counter: “When you apply for a contract with us, the credit search will remain on file for 12 months. After this, it's automatically removed from your credit file.” So a rough patch is a year rather than a life sentence, and a plan that involves waiting a few months before applying is a real plan.
The identity check
This runs on almost every order including prepaid ones, and it normally leaves nothing on your credit file. It is a check that you exist and live where you say you do, usually against the electoral roll and the agencies' own identity data. It is also the one that fails for reasons that have nothing to do with money: somebody who has moved recently, or has never registered to vote, or has been in the country a short time, can have a spotless financial record and still be hard to verify.
The serviceability check
A technical question about the street rather than about you, and the only one of the four that has no consumer dimension at all. It asks whether the address can take the service ordered. A refusal here is about cabling, and it is worth telling apart from the others, because an order that fails on serviceability can read as a rejection when nobody has looked at your file at all.
Who says a broadband order is a hard search
Direct answer: Not us. Four of the largest UK retailers publish it about themselves, in their own words, on their own sites.
This is the point where this page most sharply contradicts the version it replaces, and the previous version had thirteen providers in a table with a check type against each. Ten of those were labelled as running a soft search at the order stage. Here is what the companies actually publish.
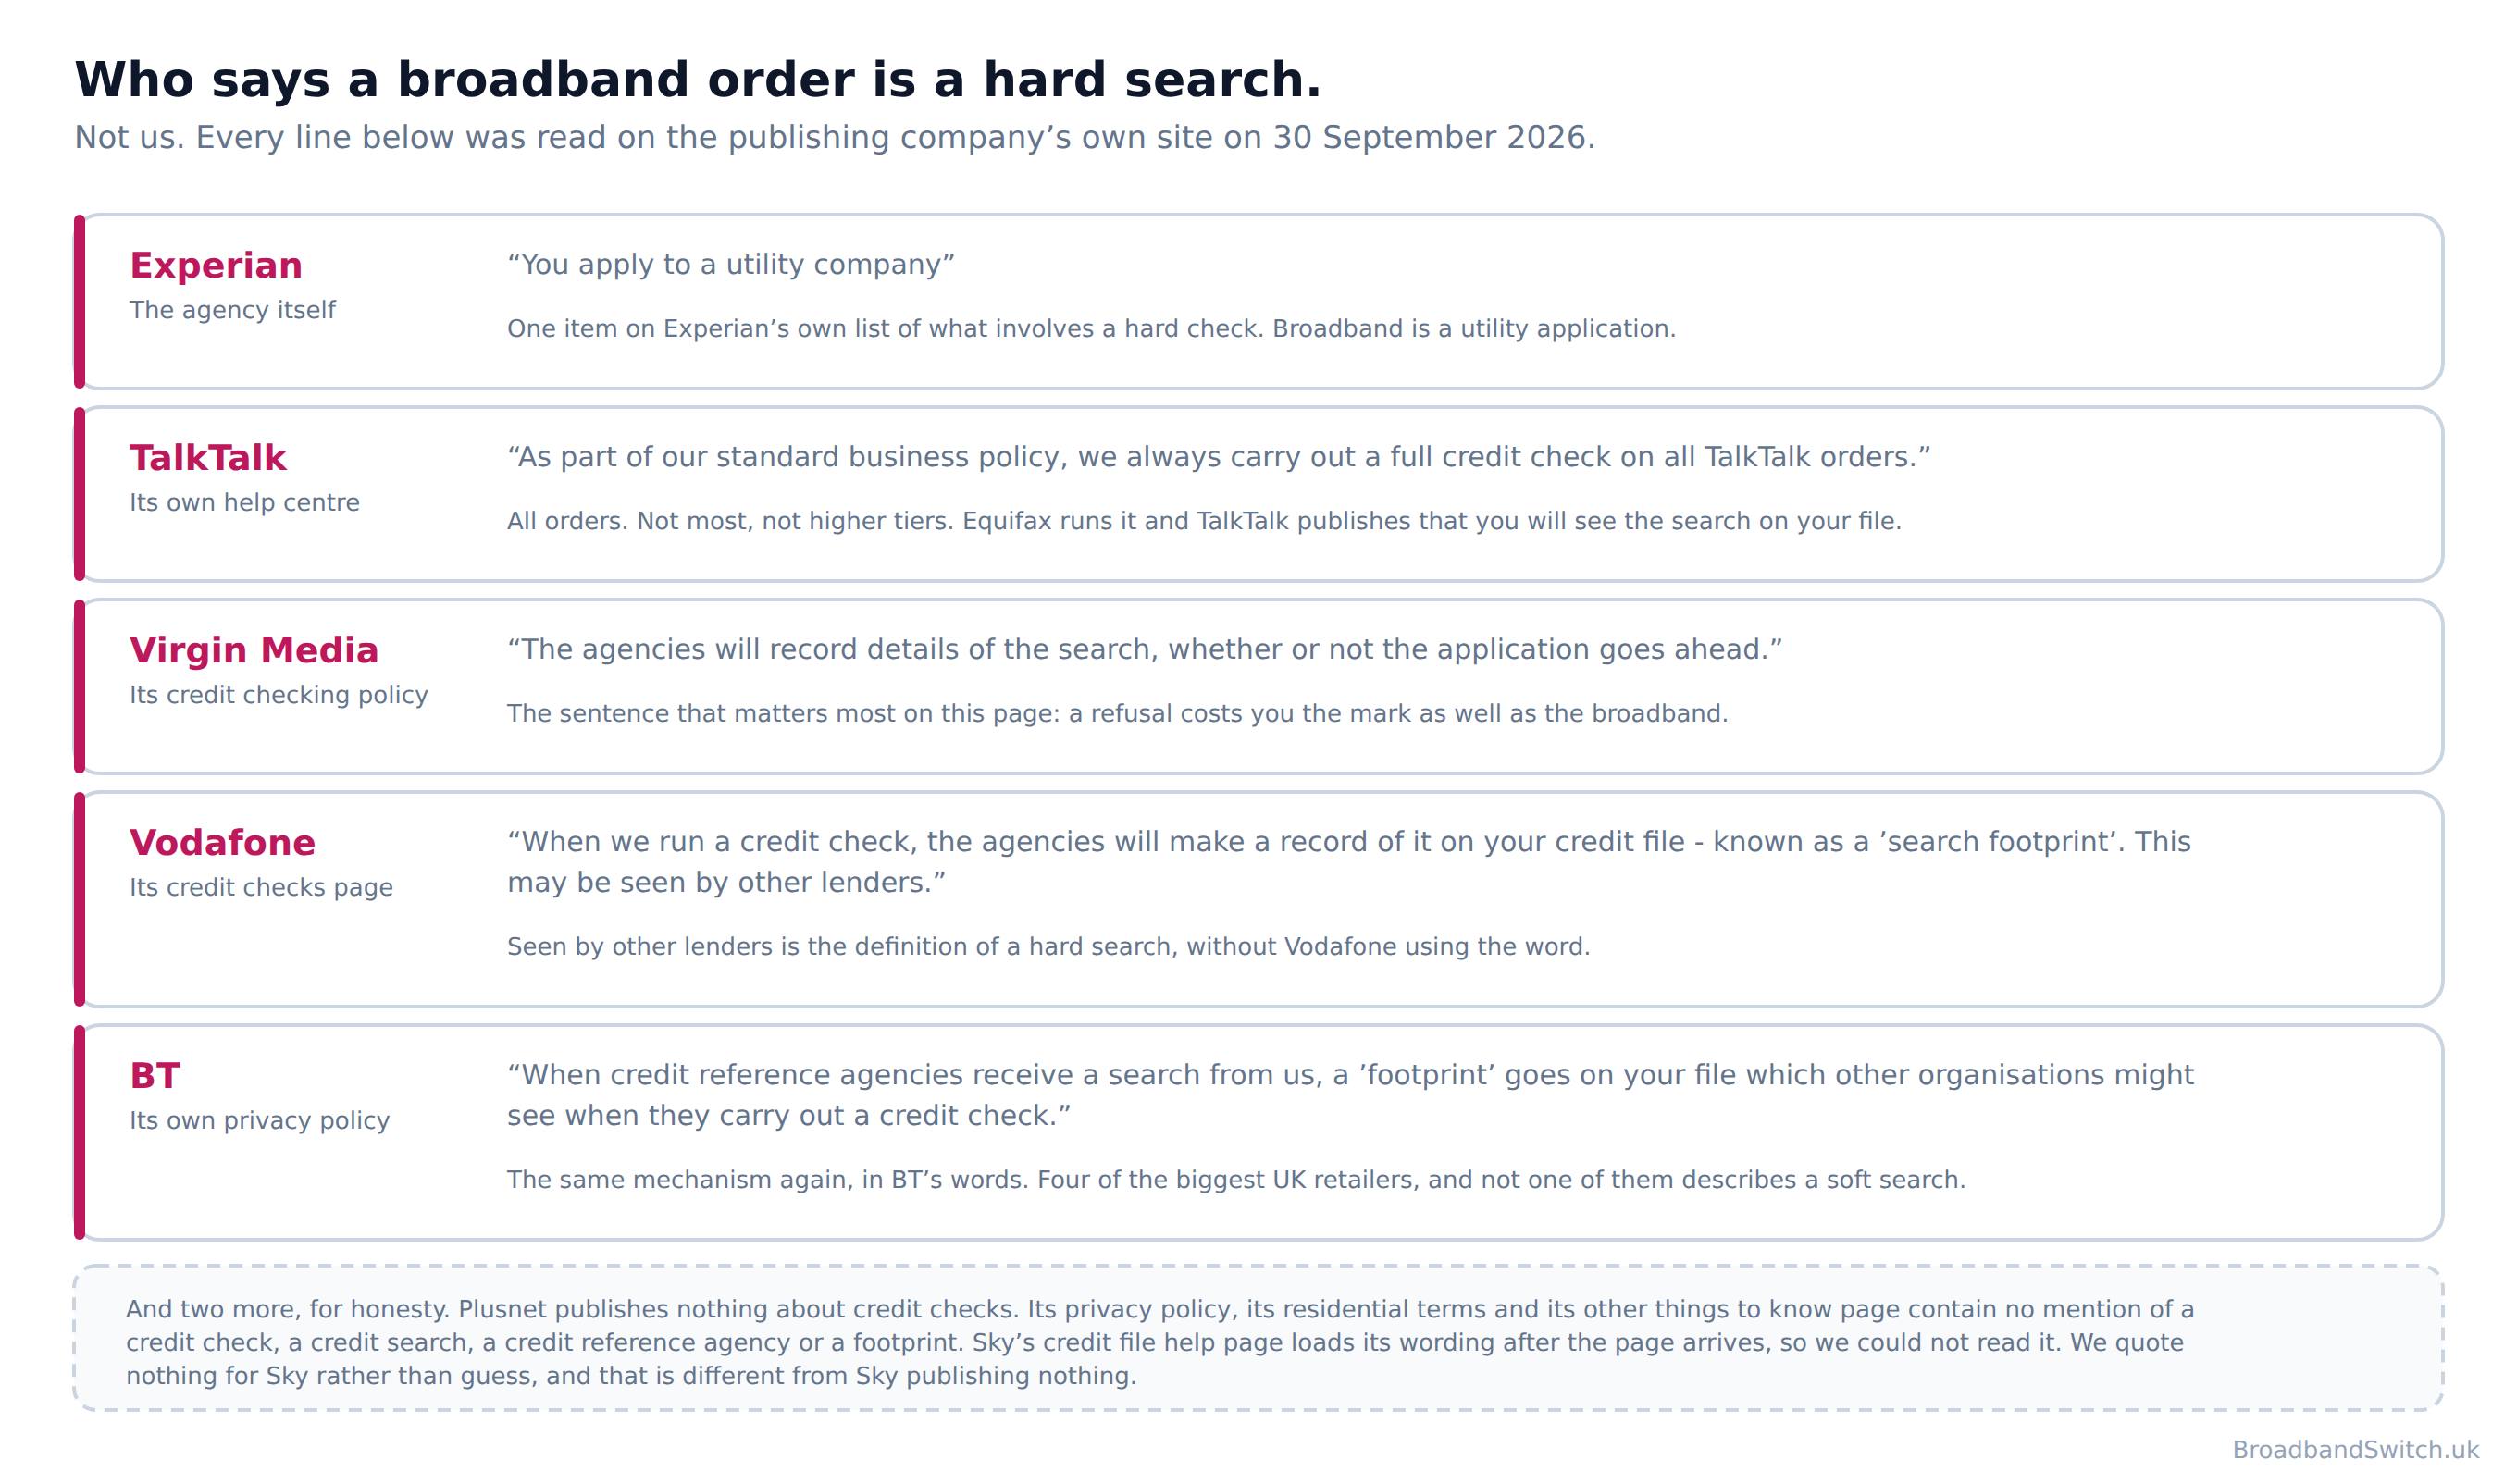
TalkTalk is the least ambiguous. Its own help centre, last modified 3 September 2025, says: “As part of our standard business policy, we always carry out a full credit check on all TalkTalk orders.” Not most orders and not premium tiers. It names the agency, “Credit checks are carried out on our behalf by Equifax, an independent credit agency.”, and then says what you will see: “Once Equifax run the credit check, you'll see a credit search from TalkTalk on your credit file.” A search you can see on your own report is one other lenders can see too, which is the definition of the hard kind.
Virgin Media's credit checking policy is broader than people expect in two directions. On timing: “We are entitled to carry out a credit check on you at any time.” Not only at the order, and not only once. And on the record: “The agencies will record details of the search, whether or not the application goes ahead.”
That second sentence is the most useful one any provider publishes on this subject, and it is the reason the advice on this page is to apply once. The footprint is the search, not the outcome, so a decline costs you the same mark an acceptance would. Somebody applying to four providers to see who will have them can end up with four marks and no broadband.
Vodafone and BT both describe the mechanism without using the word. Vodafone: “When we run a credit check, the agencies will make a record of it on your credit file - known as a 'search footprint'. This may be seen by other lenders.” BT: “When credit reference agencies receive a search from us, a 'footprint' goes on your file which other organisations might see when they carry out a credit check.” A record on the file that other companies may see is a hard search however it is described, and neither page contains the word soft.
What Virgin Media does instead of simply refusing
Worth knowing, because a failed check is not always the end of it. Virgin Media's policy lists three things it may do, and the one most people have heard of is the last: “Demand a deposit from you.” The other two are demanding payment for future line rental and usage charges, and enforcing credit limits and suspending some or all of the services. None of the seven providers on this page publishes an appeal process, so this page does not tell you there is one.
Three more, and one of them is encouraging
EE publishes the part that expires, which nobody worries about enough and everybody should: “When you apply for a contract with us, the credit search will remain on file for 12 months. After this, it's automatically removed from your credit file.” Twelve months, and then the record of the application is gone. That is a short enough horizon to plan around and it is the reason this page keeps saying that waiting is a real strategy rather than a brush-off.
giffgaff and Smarty are the two that publish a no, and both of them explain why rather than simply asserting it. Smarty: “We believe anyone should be entitled to mobile with no credit check. Because you pay upfront, we don't need to know your credit history.” giffgaff: “in most cases, we won't be doing any credit checks”, and on the one exception, “We'll only carry out a credit check if you buy a phone on a contract with a loan.” The common thread is the absence of a debt: where nothing is owed there is nothing for a model to weigh, and that is a structural answer rather than a generous one.
The two absences, named rather than filled
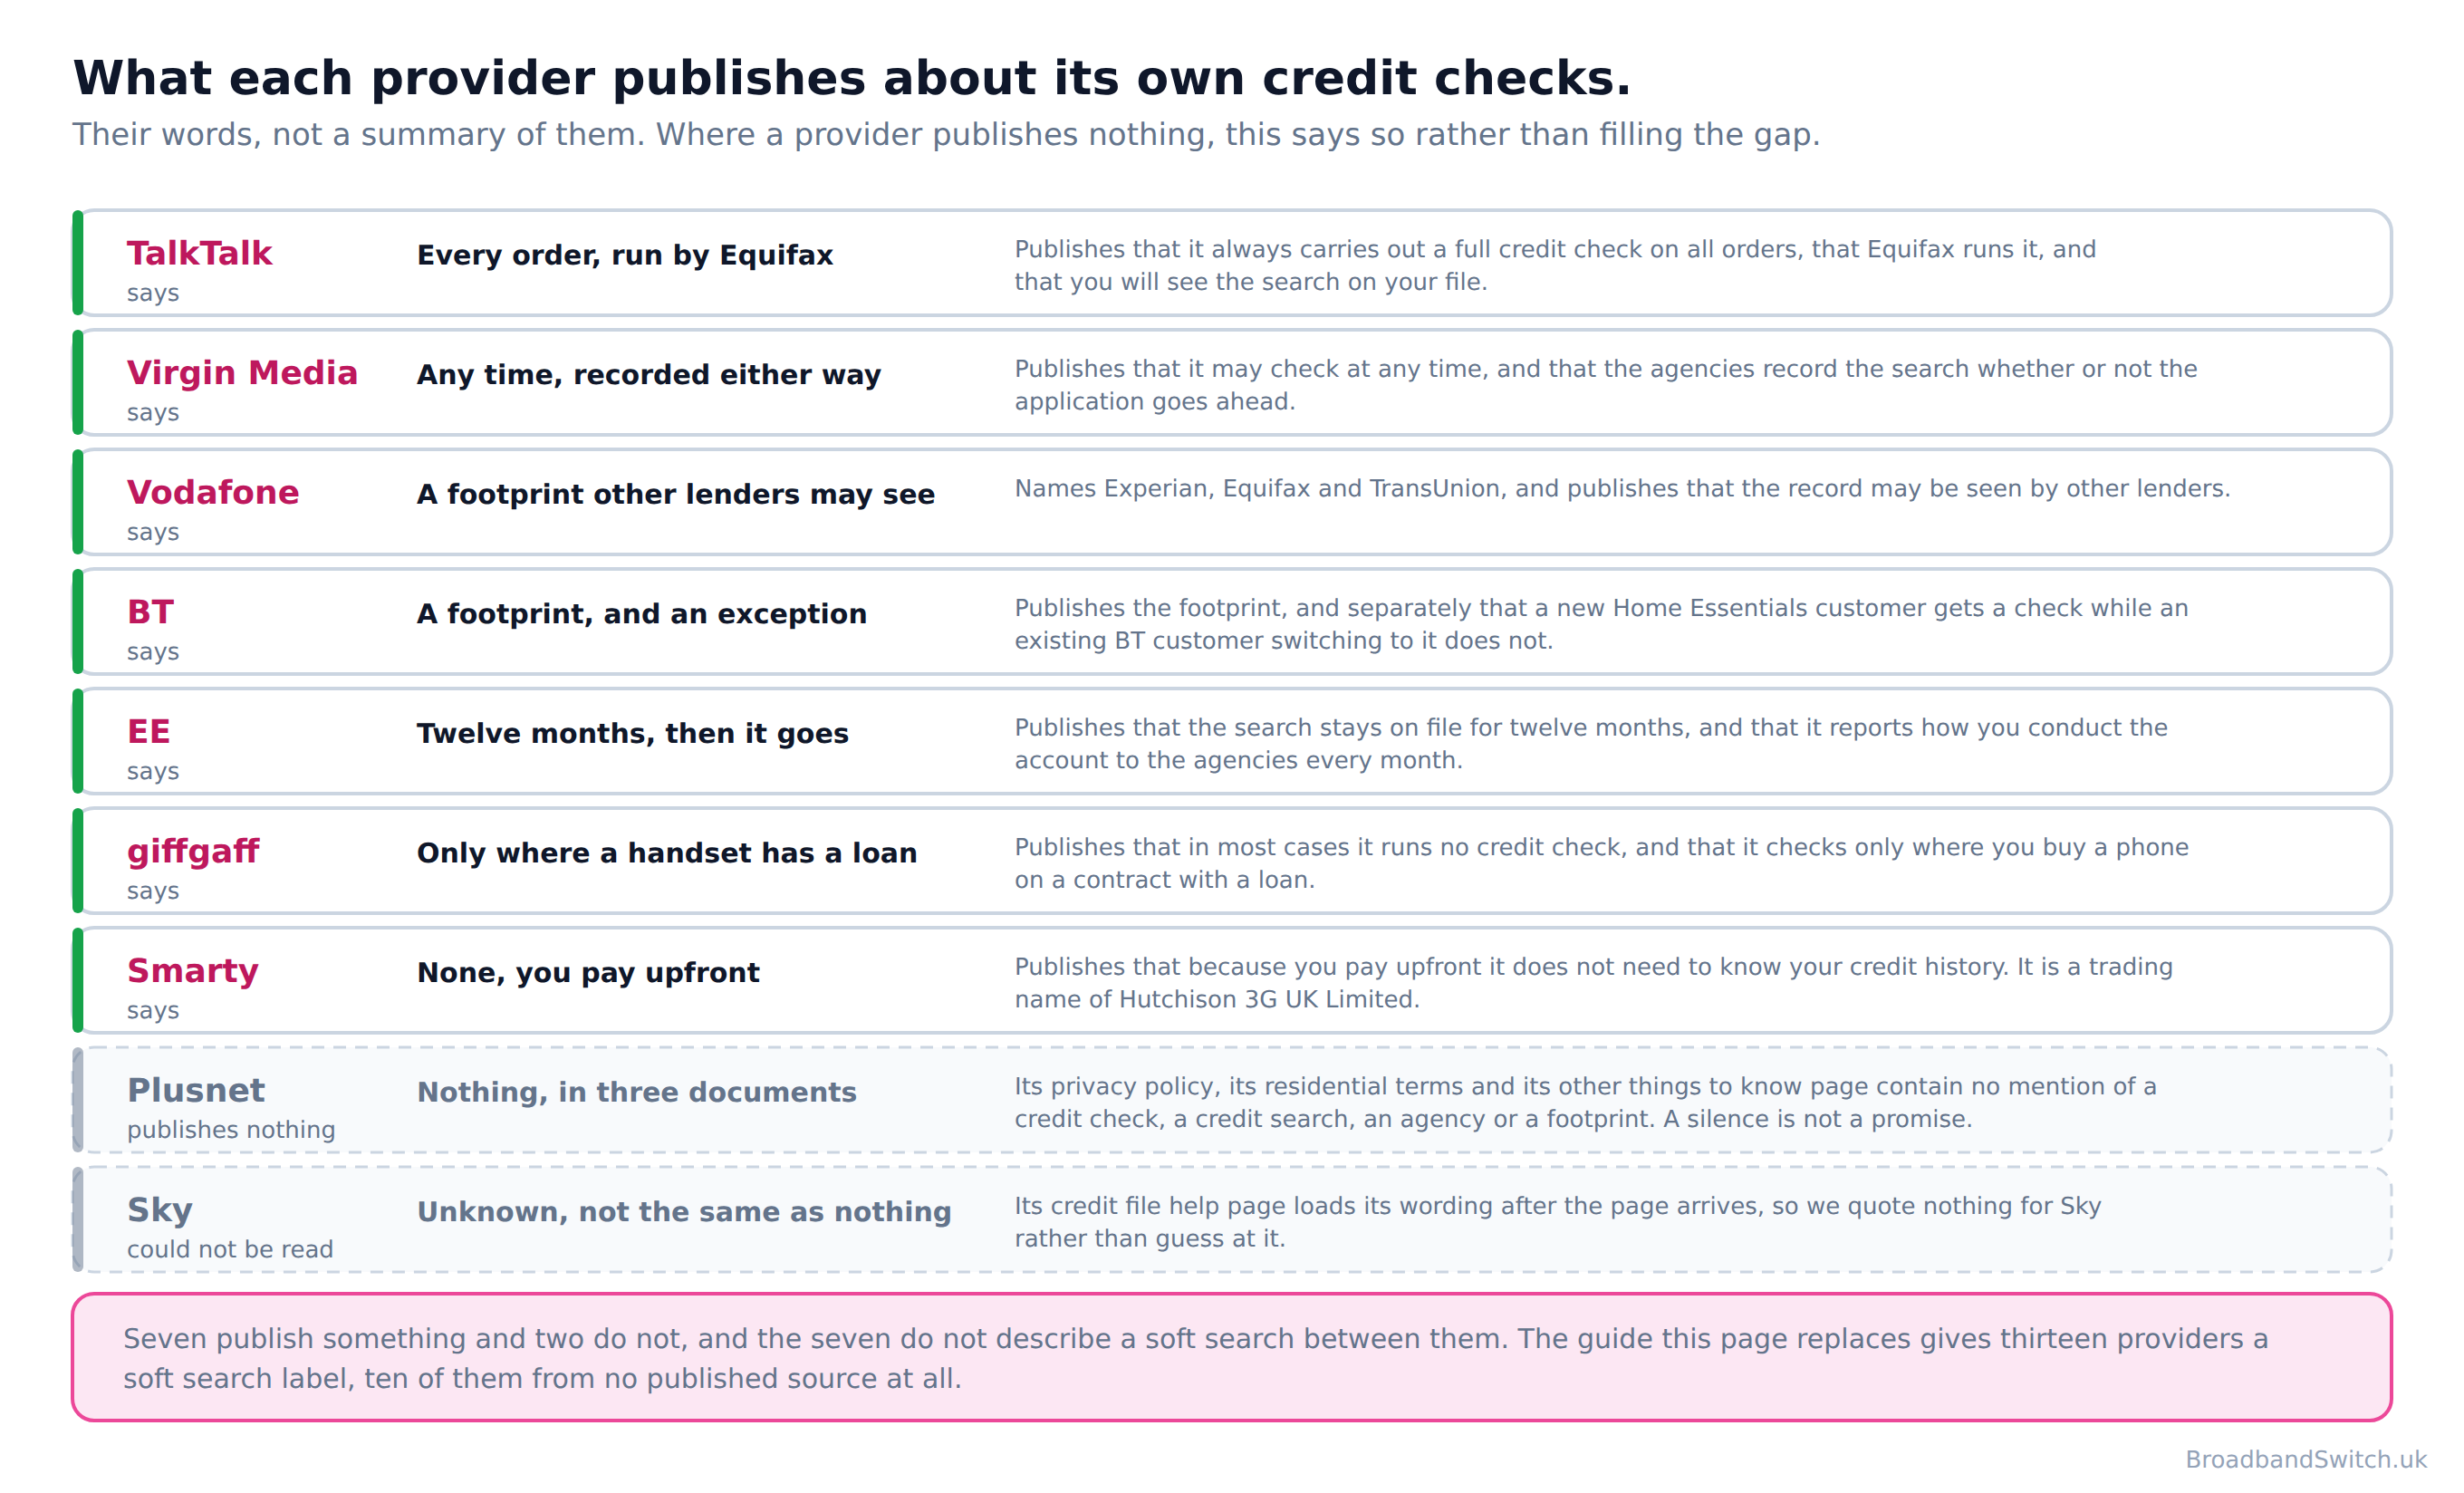
Plusnet publishes nothing about credit checks. Its privacy policy, its residential terms and its other things to know page contain no mention of a credit check, a credit search, a credit reference agency or a footprint. We have recorded that as a silence rather than as a lenient policy, because a company that has never written its practice down has not promised anything.
Sky's credit file help page loads its wording after the page arrives, so we could not read it. We quote nothing for Sky rather than guess, and that is different from Sky publishing nothing. Those two are different states and a table that turns them both into a tick or a cross is inventing information. The version of this page we replaced gave both of them a check type.
What will be searched at your address
Direct answer: Three questions. Five routes, sorted by what each one leaves on your file, with the rule behind each quoted.
It sorts by consequence rather than by price, because the price is on every comparison table already and this is not. Where a provider publishes nothing the checker says to ask rather than guessing, and where a route is not open to you on your answers it says that instead of pretending.
It runs entirely in your browser. There is no form to submit, nothing sent to any server and nothing stored: what you answer here is used on this page and gone when you close the tab. That is not a nicety on a page about credit files. Every rule it quotes was read on the publishing company's own site on 30 September 2026.
Three questions, and five routes sorted by what they leave on your file
Five routes, sorted by what each one leaves on your credit file rather than by what it costs, with the rule behind every answer quoted from whoever published it. Nothing you answer here leaves your browser.
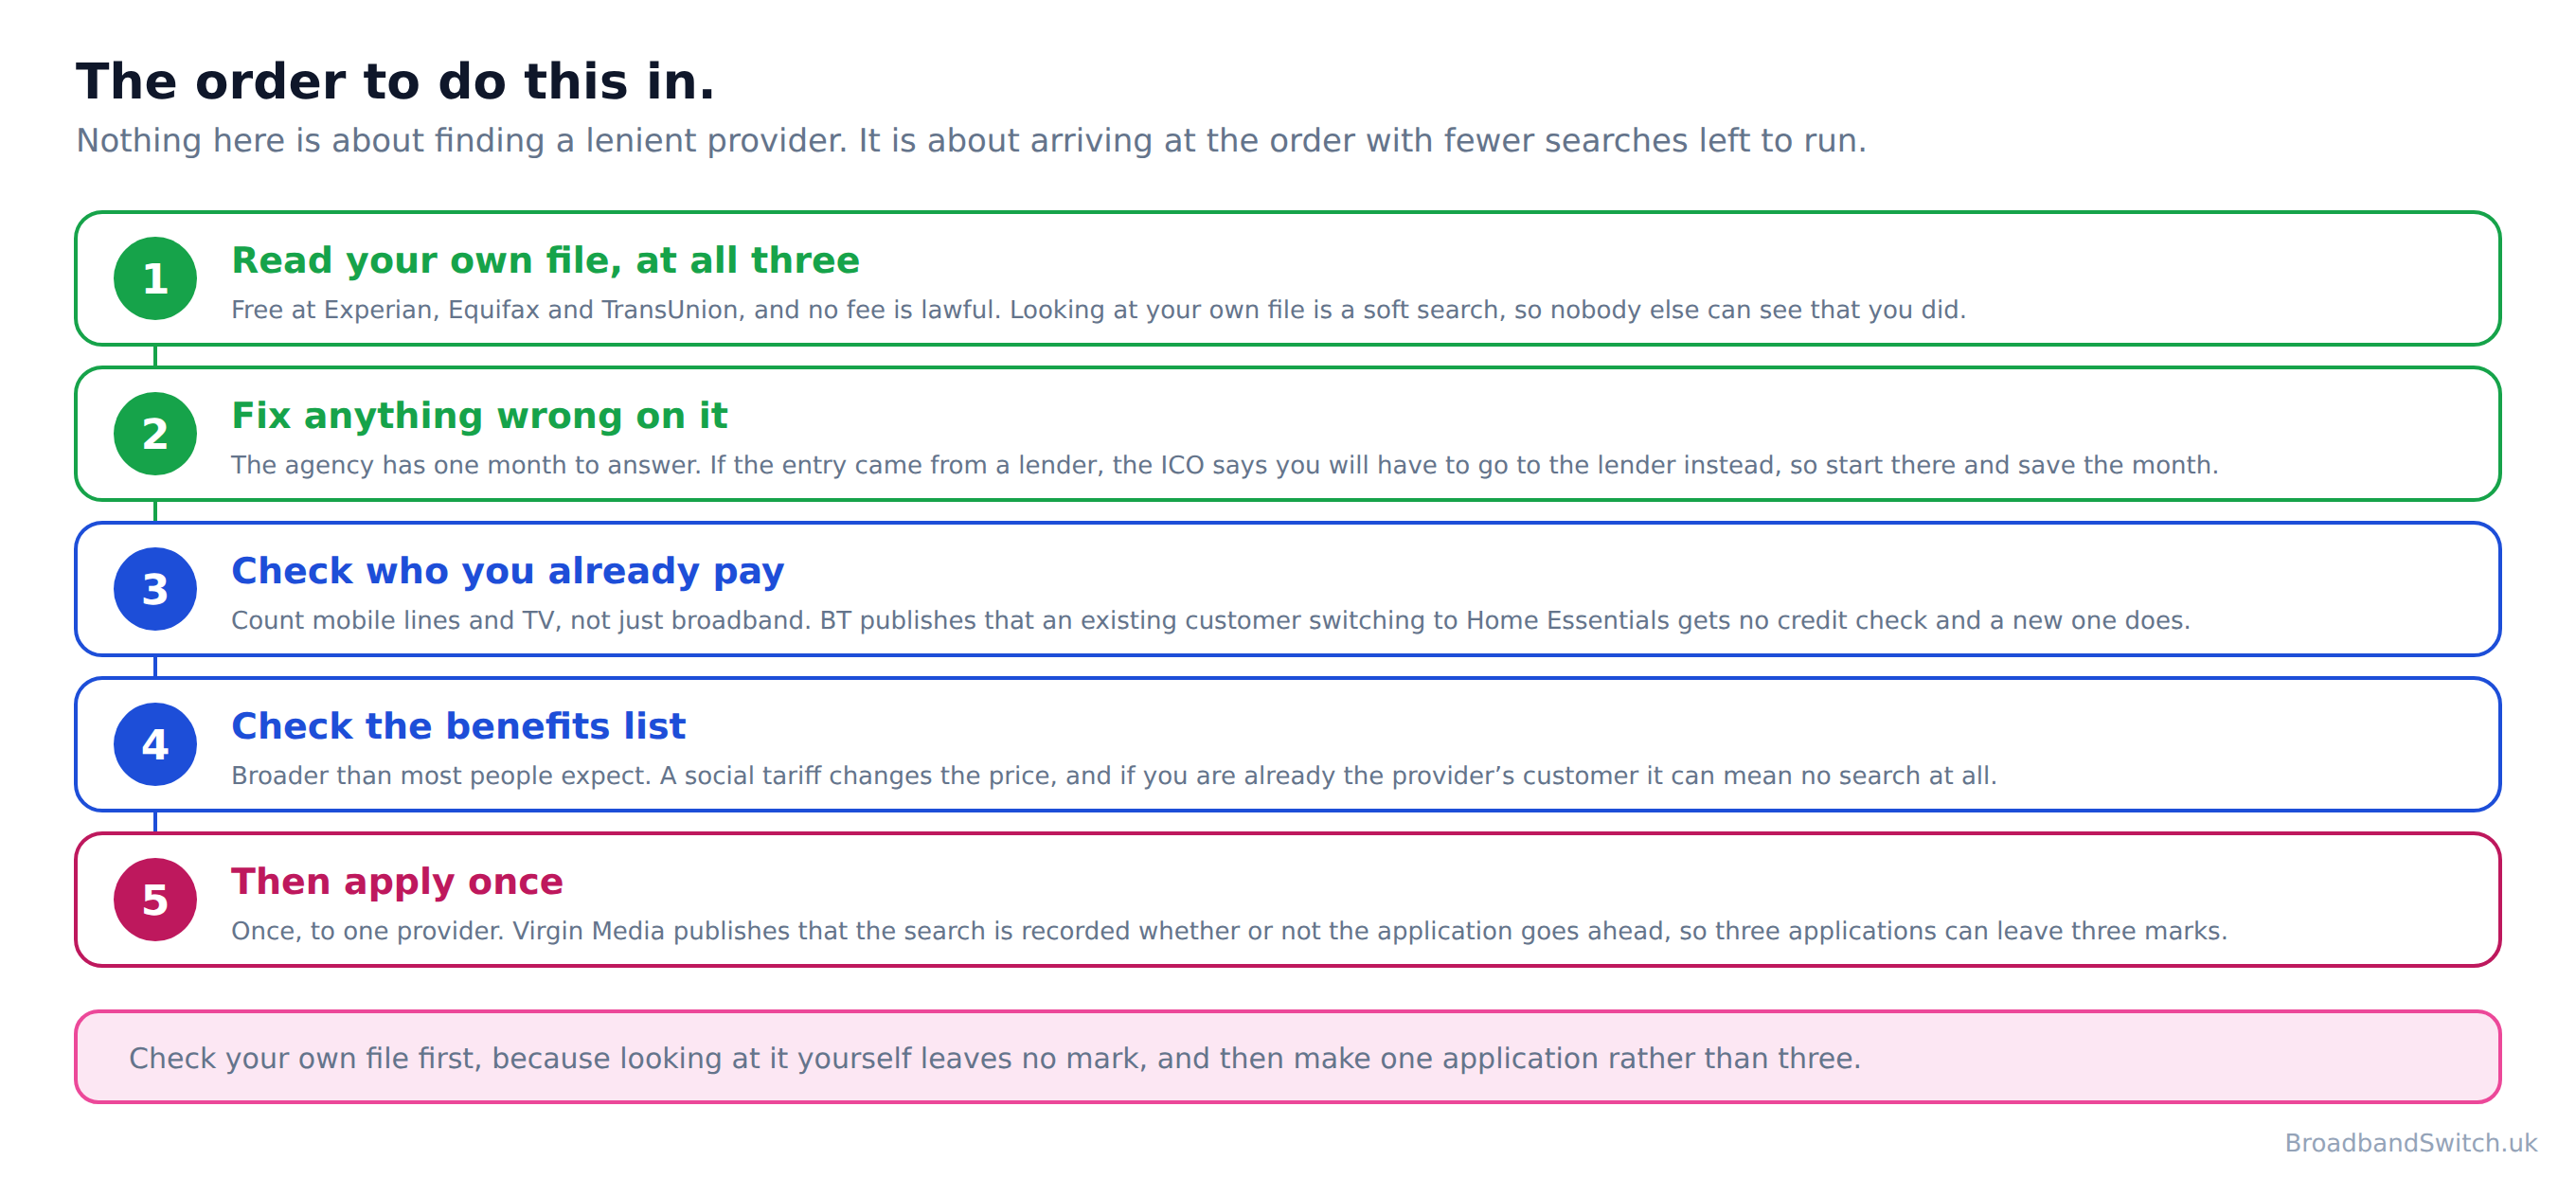
The order to do this in
Direct answer: The same tariff from the same company can cost you a hard search or nothing at all, depending on which order you do things in.
BT publishes both halves of that on one page, under a heading about eligibility, and it is the most useful pair of sentences in the subject. On a new customer: “If you're new to BT, we'll carry out a credit check as part of your application.” And on somebody who is already with them: “If you're an existing BT customer switching to Home Essentials, we won't carry out a credit check.”
Nothing about that is hidden and nothing about it is unfair. It is simply that the sequence decides the outcome, and the sequence is not something anybody mentions at the point you are making the decision.
Count everything you already pay for
Most people answer this question about broadband alone, and the account that helps might be a mobile line or a TV package. BT, Sky, Virgin Media, Vodafone and EE all sell more than one thing, so a household with a mobile contract at one of them may already be an existing customer of a company that also sells the broadband they want.
The one thing not to do is cancel and reapply. Cancelling makes you a new customer, and a new customer gets the check. If the plan you want is only advertised to new customers, that is a conversation to have with the provider before you cancel anything, not afterwards.
Ask in writing, and ask the specific question
The question that gets a useful answer is narrow: will moving me to this plan involve a credit search, and will it be recorded on my file. A chat transcript or an email is worth more than a phone call, because the answer is the thing you may need to point at later.
Only BT publishes an answer to that question in advance, and only for one tariff. Everybody else decides it case by case, which is why asking is worth the ten minutes and why this page does not print a table of who will say yes.
If a qualifying benefit is in the household
Ofcom publishes that “If your provider offers a social tariff, you can switch to it at any time, free of charge.” and that “It costs nothing to leave. You won't pay a fee to leave the tariff before the end of your contract.” So a social tariff is not a trap even if your circumstances improve. Ofcom's social tariffs page does not contain the words credit check or credit search anywhere. Whether a search runs is the provider's choice, not part of the scheme. BT's Home Essentials is a “12 month contract” at £16.50 a month, and BT also publishes “Cancel anytime without any early exit fees”, which is a contract with no cost to leave rather than no contract at all. Who qualifies and what each provider charges is on our UK social tariffs guide.
The routes that involve no search
Direct answer: Smarty puts the mechanism in one line: “We believe anyone should be entitled to mobile with no credit check. Because you pay upfront, we don't need to know your credit history.”
Smarty's second sentence is the whole mechanism, and it applies to every prepaid route rather than only to Smarty. Where the money arrives before the service does, there is no risk for anybody to assess, so there is nothing for a credit file to answer. It is the only route on this page that is certain rather than likely.
Smarty also publishes the terms that go with it: “No minimum term contract, the freedom to cancel at any time, and the flexibility to add more data whenever you need it.” And one thing worth knowing about who you are dealing with, because the brand is younger than the company: “SMARTY is a trading name of Hutchison 3G UK Limited”. That is the same business as Three.
giffgaff publishes the same position on its SIM plans, with a caveat this page would rather quote than smooth over: “in most cases, we won't be doing any credit checks”. In most cases, it says, which is not the same as never. What brings a check back is specific and giffgaff says so: “We'll only carry out a credit check if you buy a phone on a contract with a loan.”
The hardware is the part that is credit
A prepaid SIM avoids the search because nothing is owed. Add hardware paid off monthly and the loan comes back, and so does the search. It is worth asking who the lender is as well. The Financial Conduct Authority describes deferred payment credit as “DPC is an interest-free form of credit, repayable in 12 or fewer instalments, over 12 months or less.”, and then draws the line that decides your protections: “If you buy something from a business and use DPC that's provided by that same business, it will not be regulated.” A provider spreading the cost of its own hub is that same business. A third party lender in the middle is not, and that arrangement is regulated. Neither announces itself at the checkout. Our 4G and 5G stopgap guide covers buying a hub outright.
What each provider publishes, and where the gaps are
Seven of the nine companies checked for this page publish something about their own credit checks. Two publish nothing readable. Not one of the seven describes a soft search.
Two more routes belong here for completeness and both are somebody else's page. Where broadband is included in the rent, the contract is between the landlord and the provider rather than between you and anybody, so no personal check applies: our students guide and our short lets guide cover the accommodation side of that. And a rolling monthly contract is still a contract: our one month broadband guide and our no contract guide for renters cover what those cost.
If you have already been refused
Direct answer: The search is already recorded, so the next move is not another application.
A refusal is a scoring decision rather than a judgement about you, and it is worth being clear about what it does and does not mean. It does not mean a provider has decided you cannot pay. It means a model weighted some combination of what is on your file against how much the contract commits you to, and came out below whatever line that company draws this month. A different company draws a different line, and the same company draws a different line on a cheaper plan.
What is not in doubt is that the mark has landed. Virgin Media publishes it plainly: “The agencies will record details of the search, whether or not the application goes ahead.” So the instinct to try somewhere else immediately is exactly the wrong one, because each attempt costs another twelve months on the file and the second application is being assessed against a file that now shows the first.
A refusal is sometimes a conditional yes
This is the part nobody tells you and it is worth one phone call. Virgin Media's credit checking policy lists three things it may do where a check is not satisfactory, and only one of them is walking away. It may enforce credit limits and suspend some or all of the services. It may demand payment for future line rental and usage charges, which is to say ask you to pay ahead. And: “Demand a deposit from you.”
A deposit or an upfront payment is a real option for somebody who has the money now but not the record, and it is not usually offered unprompted. Asking what alternatives exist costs nothing and does not involve another search, because the application has already been assessed.
Ask which agency was used
The provider makes the decision and an agency supplies the data, and they are not interchangeable. Experian, Equifax and TransUnion hold different files, so an entry that sinks an application at one company may not exist at the agency the next company uses. TalkTalk names its agency outright: “Credit checks are carried out on our behalf by Equifax, an independent credit agency.” Vodafone and EE both name all three.
So the useful question after a refusal is which agency was searched, and the useful next step is to read your file at that one. It is free, it is a soft search, and it is the only way to see what the decision was actually made on.
None of the seven providers checked for this page publishes an appeal process, so this page does not tell you there is one. What you can ask for is the specific reason and the agency used, and both of those are ordinary customer service questions rather than a challenge.
What not to do next
Do not apply to three more providers this afternoon. Do not cancel an existing account with a company you might have moved within, because cancelling turns you into a new customer and a new customer gets the check. And do not pay anybody for a credit repair service: everything on this page that works is free, and the report that shows you what went wrong costs nothing at any of the three agencies.
If you have no UK credit history at all
Direct answer: A thin file is a different problem from a poor one, and the check that fails is often not the credit check.
This is the position of most people who have recently arrived in the UK, a good many students, and almost everybody under about twenty one. It also catches somebody who has moved house three times in two years, or who has never registered to vote, or who has always paid for everything outright. Nothing about any of that is a financial problem, and it can still produce the same answer at the checkout. Our students guide covers the accommodation side of it.
The check that usually fails here is the identity one rather than the credit one. A provider is trying to confirm that you are a real person living where you say you live, and the records it looks at are the electoral roll, public records and the agencies' own identity data. Somebody with no entries in any of those is hard to verify, and being hard to verify looks the same from the outside as being risky even though it is a completely different thing.
Start with something that needs no history
Prepaid is the obvious first move and it is the one route that cannot involve a credit search. Smarty gives the reason: “We believe anyone should be entitled to mobile with no credit check. Because you pay upfront, we don't need to know your credit history.” There is nothing to assess when the money has already arrived. That gets a household connected this week rather than after a process, and it buys the time the rest of this takes.
Then register to vote if you have not, because the electoral roll is the single record that does most to make somebody verifiable, and it is free. And keep one address stable for as long as you reasonably can, because linked and changing addresses are a large part of what makes a file hard to read.
Then let an ordinary bill do the work
EE publishes the mechanism, and it is the most encouraging sentence in this whole subject: “We make a record of how you conduct your account. This information is provided to the agencies automatically each month.” A telecoms account paid on time reports to the agencies every month, which means a modest contract quietly builds a record while it runs. Nothing else on this page builds a record while you are not thinking about it, and it is a bill you were going to pay anyway.
So the sequence for a thin file is prepaid now, one modest contract when you can get one, and a better one later, rather than aiming high and collecting refusals. A hard search drops off after twelve months and a record of payments made on time does not, which means time is on your side here in a way it rarely is.
One thing worth knowing about identity failures
An order that fails identity verification can read exactly like a credit refusal, and it is not one. If you are new to the country or have just moved, it is worth asking which check failed before you assume anything about your file, because an identity problem is solved with a document and a credit problem is solved with time. They are not the same conversation and they do not have the same answer.
Fixing something that is wrong
Direct answer: Start with whoever put the entry there, because the agency often cannot change it.
This is the part of the process most guides get half right, and the half they miss costs a month. The ICO's own consumer page sets out where a complaint goes: “raise your complaints with the relevant CRA you obtained your file from. However, the problem may lie with the original lender or organisation that supplied the CRA with the information so you will need to contact them instead.”
So the useful first question is not whether the entry is wrong, it is where it came from. A default recorded by a lender belongs to that lender. An address linked to you in error, or an electoral roll record that is out of date, is more likely to be the agency's own. Sending the right complaint to the right place first is the difference between one month and two.
The clock is published and it is worth holding people to. “Unless the CRA needs more information, they have one month from receiving your request to respond. In certain circumstances they may need extra time to consider your request and can take up to an extra two months.” The page this one replaces gives seven working days, which is a service level some agencies advertise rather than the period you are entitled to.
The cheapest credit repair there is
EE publishes something most people never think about: “We make a record of how you conduct your account. This information is provided to the agencies automatically each month.” A broadband or mobile account paid on time reports to the agencies every month, which means an ordinary bill quietly builds a record while it runs. For somebody with a thin file, a prepaid SIM for a few months followed by a modest contract paid on time is a plan rather than a holding pattern.
What we could not find out
Direct answer: Six questions a reader would reasonably ask that nobody publishes an answer to.
Most guides on this subject fill those six gaps with a plausible sentence, and a plausible sentence about somebody else's internal policy is a guess. Publishing the gaps instead is less satisfying and it is the only version that stays true next quarter, so here they are.
What Sky does
Sky's credit file help page loads its wording after the page arrives, so we could not read it. We quote nothing for Sky rather than guess, and that is different from Sky publishing nothing. It is worth being precise about the difference, because a table that shows a blank for both looks the same and is not. A company that publishes nothing has said nothing. A company whose page we could not read may well have said something useful.
What Plusnet does
Plusnet publishes nothing about credit checks. Its privacy policy, its residential terms and its other things to know page contain no mention of a credit check, a credit search, a credit reference agency or a footprint. A silence is not a promise and it is not an accusation either. It means the honest answer to what Plusnet runs is that you would have to ask them, and that any guide telling you otherwise has got it from somewhere other than Plusnet.
Whether a shorter contract is easier to pass
It is the most common piece of advice in this subject and no provider publishes anything that supports it. The intuition is reasonable, because a shorter commitment is a smaller risk. What is actually published cuts the other way: TalkTalk says “As part of our standard business policy, we always carry out a full credit check on all TalkTalk orders.”, with no tier or term attached to it, and Virgin Media reserves the position entirely with “We are entitled to carry out a credit check on you at any time.” So this page does not tell you a rolling plan will get you through where a two year one would not. What it can tell you is that paying upfront removes the question, because then there is no contract to assess.
Whether a formal debt arrangement rules you out
None of the nine companies checked for this page publishes a policy on bankruptcy, an individual voluntary arrangement, a debt relief order or a debt management plan. Not one mentions any of them. So a guide that tells you which providers accept people in an IVA is describing something no provider has published, and this one will not repeat it.
What is published, and what actually helps, is the structure: the prepaid route involves no assessment at all, and a social tariff turns on a benefit rather than on a file. Both of those are open whatever is on your record, and neither depends on a provider taking a view about a formal arrangement.
Whether a failed check can be appealed
Nothing any of the seven publishing providers says describes an appeal, a review or a second look. That absence is why this page tells you to ask which agency was searched rather than to ask for a reconsideration: one of those is a question with a published answer behind it and the other is not.
Whether the social tariff schemes protect you from a search
Ofcom's social tariffs page does not contain the words credit check or credit search anywhere. Whether a search runs is the provider's choice, not part of the scheme. Ofcom publishes a great deal about social tariffs, including that “If your provider offers a social tariff, you can switch to it at any time, free of charge.”, and nothing at all about whether a provider may run a credit check before putting you on one. BT is the only provider that publishes its own position, and that position has two halves depending on whether you are already its customer.
Which regulator, and the free route
Direct answer: Broadband is Ofcom's, not the FCA's. If a provider has treated you badly over a credit decision, the route is the provider's own complaints process and then one of two free schemes, not the Financial Ombudsman.
The guide we replaced says the opposite, at length, and this is the correction most likely to have cost somebody a real outcome. It names the Financial Conduct Authority eighteen times, describes broadband contracts as regulated credit four times, and builds a whole section on affordability assessment as a regulatory obligation.
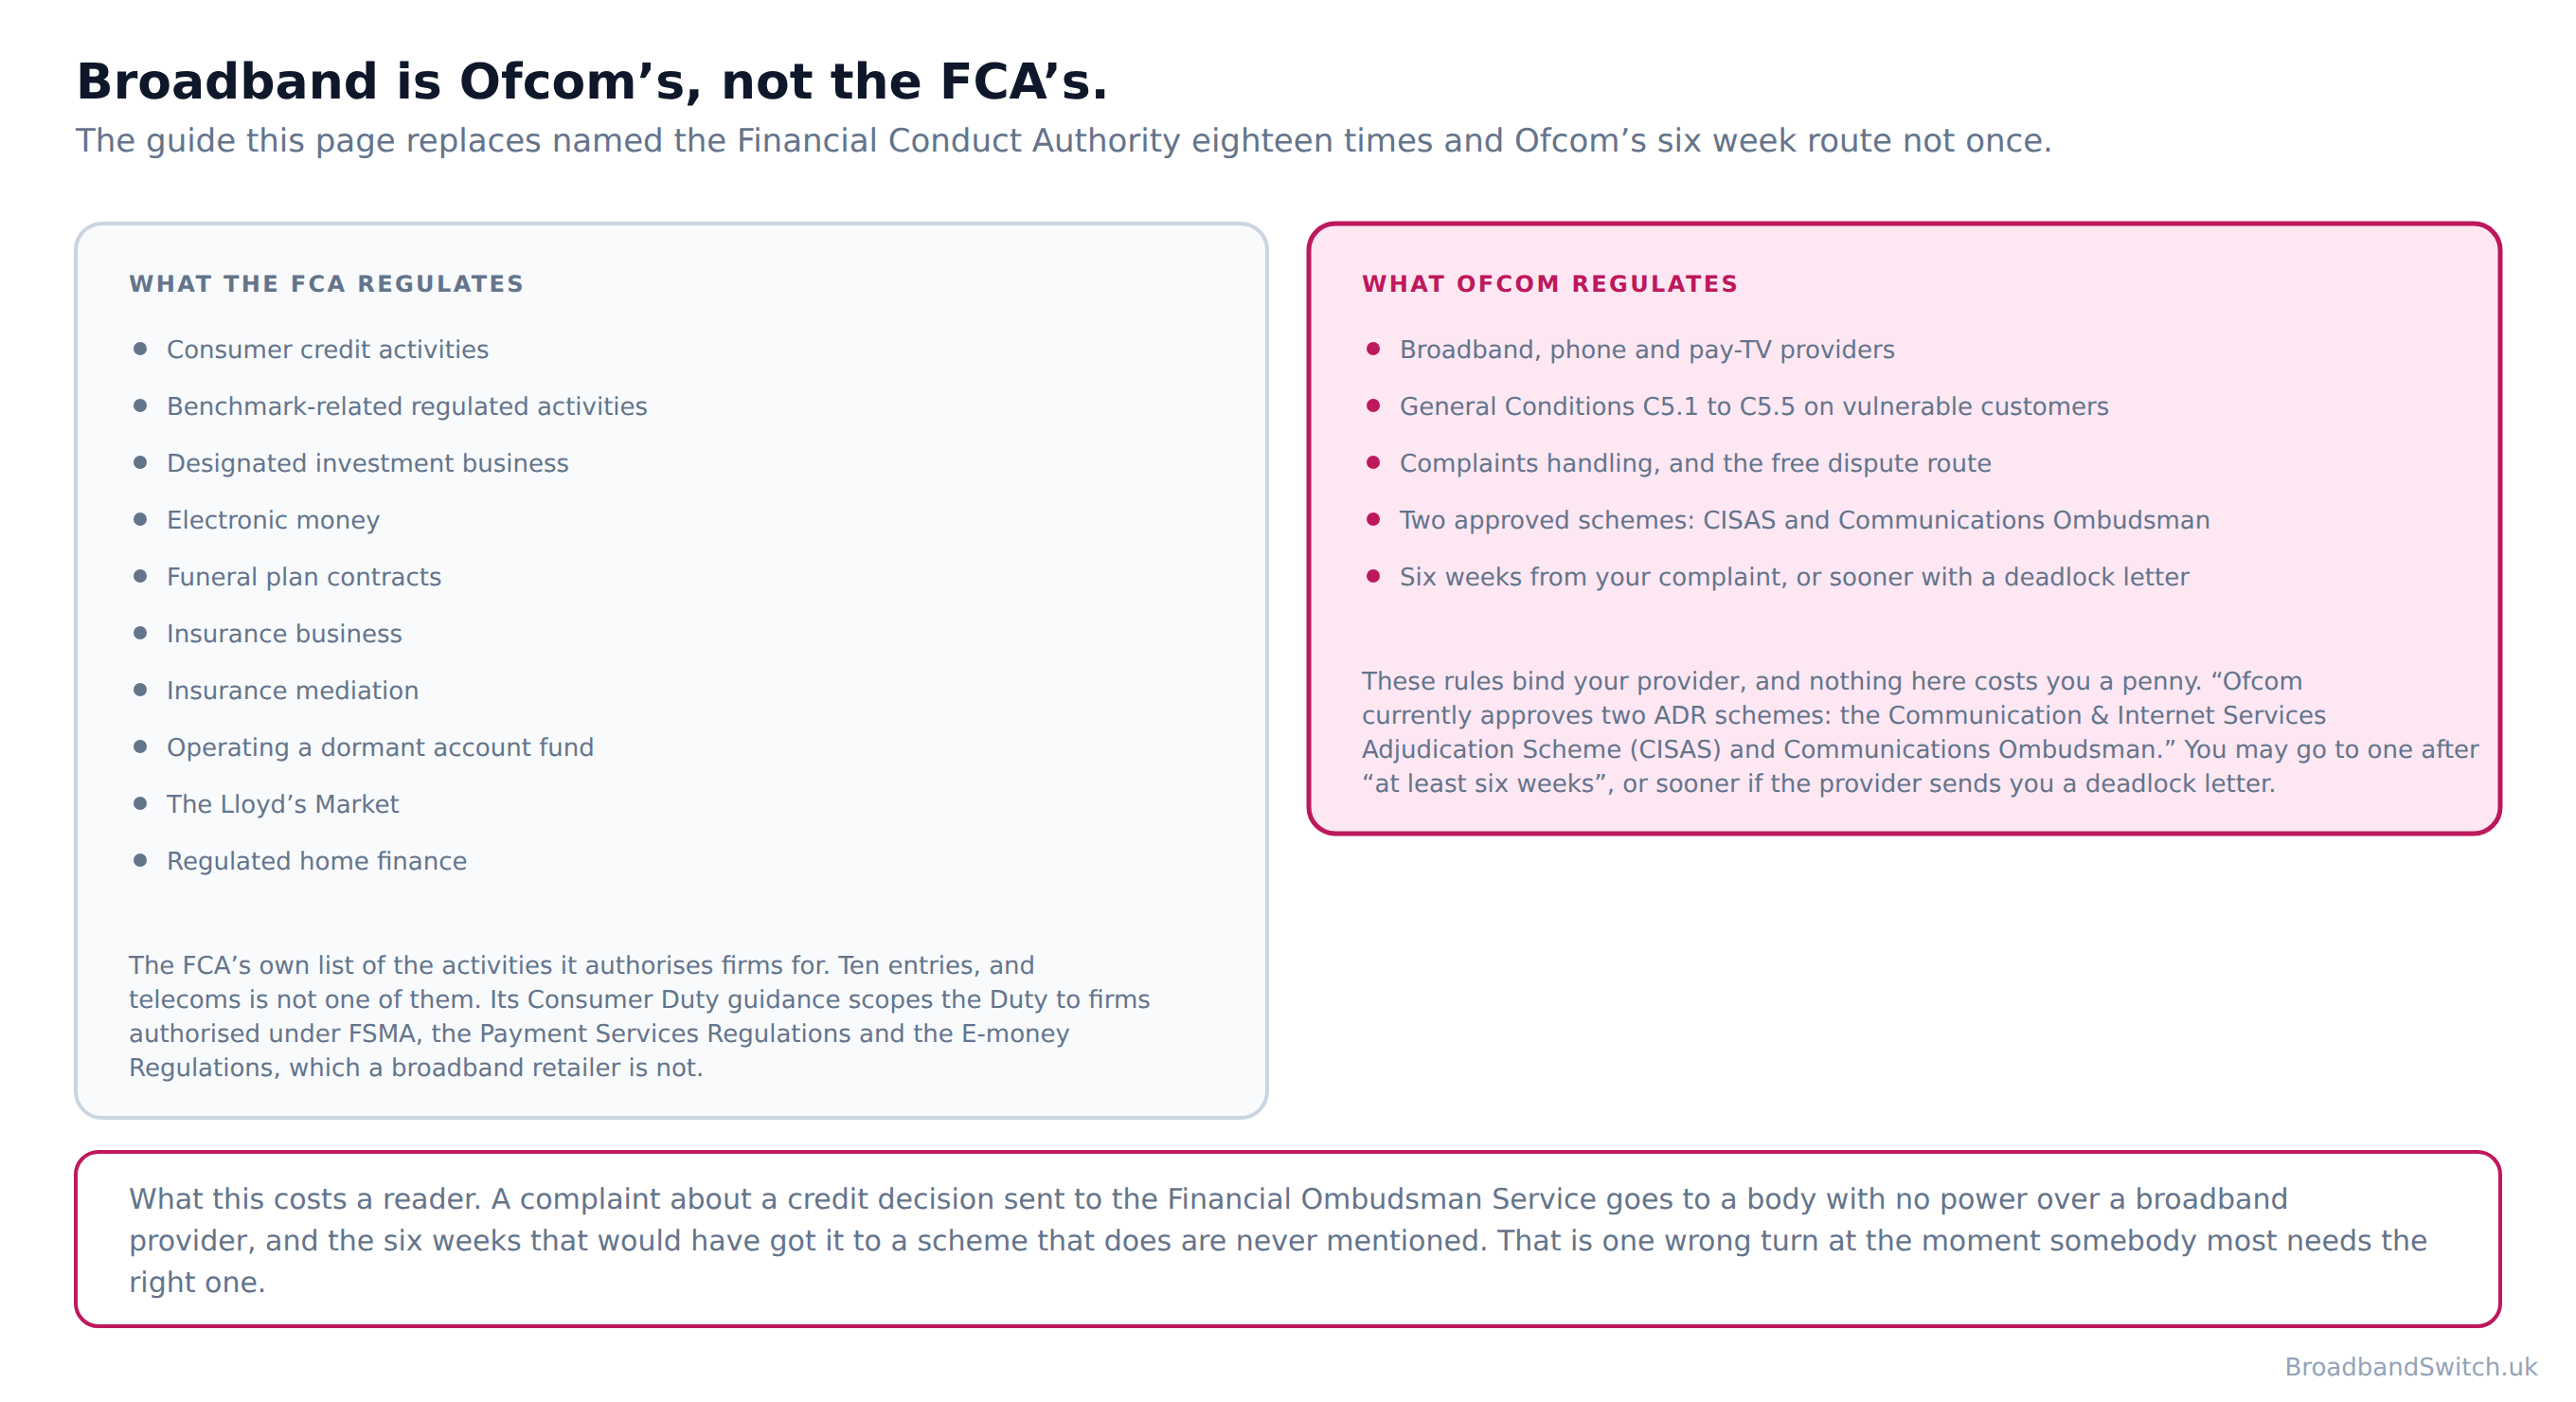
The FCA publishes a list of what it authorises firms to do, and it runs to ten entries: Consumer credit activities; Benchmark-related regulated activities; Designated investment business; Electronic money; Funeral plan contracts; Insurance business; Insurance mediation; Operating a dormant account fund; The Lloyd's Market; Regulated home finance. There is no telecoms category and no communications category. Its Consumer Duty guidance is explicit about who the Duty reaches: “The Duty applies to the regulated activities and ancillary activities of all firms authorised under the Financial Services and Markets Act 2000 (FSMA), the Payment Services Regulations 2017 (PSRs) and E-money Regulations 2011 (EMRs), in respect of products and services for prospective and actual retail customers.” A broadband retailer holds none of those three permissions.
Affordability is not one of the Duty's four outcomes either. They are the governance of products and services; price and value; consumer understanding; consumer support. So even for the firms it does cover, a page describing the Duty as an affordability requirement has the wrong end of it.
What Ofcom's rules actually give you
Ofcom's protections for people in difficulty are real, they bind your provider, and they are broader than most readers expect. General Conditions C5.1 to C5.5 have been in force since October 2018, “requiring providers to have policies and procedures in place to make sure vulnerable customers are treated fairly”. And the definition Ofcom works to: “Anybody can face circumstances that lead to them becoming vulnerable - temporarily or permanently. This might include physical or mental health problems, specific characteristics such as age or literacy skills, or changes in personal circumstances such as bereavement, job loss or changes in household income.” Changes in household income is the phrase that covers most people who arrive on a page like this one.
One honest limit belongs with that. Ofcom's vulnerable customers guide does not mention credit checks, credit searches or affordability anywhere. The protection is about how you are treated, not about whether you pass a search. Telling a provider about your circumstances may get you a payment arrangement, an accessible format or more time. It will not get you past a credit decision, and a guide that implies otherwise is setting somebody up for a disappointing phone call.
The route that works, and the detail that makes it usable
Complain to the provider first, and if that goes nowhere: “Ofcom currently approves two ADR schemes: the Communication & Internet Services Adjudication Scheme (CISAS) and Communications Ombudsman.” You may take it to one of them “at least six weeks” after you first complained, or sooner if the provider gives you a deadlock letter.
The page we replaced named both of those schemes five times and never once said how long you have to wait, which is the only detail that turns a name into a route. Without it a reader either goes too early and is sent away, or decides the whole thing is theoretical.
The enforcement case, corrected
The guide we replaced cites an Ofcom penalty twice as an affordability enforcement example. Ofcom's own headline is “Ofcom fines Virgin Media £23.8 million for putting vulnerable customers at risk of harm”, and the condition breached requires a provider to “establish, publish and comply with clear and effective policies and procedures for the fair and appropriate treatment of consumers whose circumstances may make them vulnerable”. The fine was about telecare customers during the move from analogue to digital landlines. Ofcom found Virgin Media failed properly to identify and record the status of telecare customers, and disconnected telecare customers who did not engage in the migration process. The word cable appears nowhere in the decision, and neither do credit checks, affordability or the FCA. It is a serious case about something else, and using it here suggested a body of credit-related enforcement that does not exist.
Broadband at your postcode
Direct answer: Worth looking before you apply anywhere, because knowing your options is what lets you apply once.
The whole argument of this page is that one application beats three, and one application is only possible if you have already decided which provider you want. That decision is what a comparison is for: see everything that reaches the address, pick the one you actually want, and then apply to that one.
Every provider that reaches your address
One postcode shows every provider that reaches the address, lowest price first, across full fibre, FTTC, cable and 5G home broadband. Decide first, then apply once.
Show every provider at my postcode →What this page used to say, and why it changed
Direct answer: Five corrections. Two of them cost a reader money or sent them to a regulator with no power over their provider.
Publishing these rather than quietly editing is the only way somebody who acted on the old version can tell whether they acted on something wrong. On this page that matters more than usual, because the reader the errors would have reached is by definition the one with least room to absorb them.
Charging for three reports that are free
What this page said
The page said UK consumers have a statutory right to a credit report “for a maximum statutory fee of £2 per report”, named the £2 fourteen times, carried it as one of four headline statistics, and printed the postal addresses to send the money to. Three agencies at £2 each is about £6, from a guide whose own opening section is free debt help.
What it says now, and why
The Information Commissioner’s Office says: “You have the right to request a copy of the information held about your financial standing from any of the CRAs. Making this request is free of charge.” It also tells you the phrase to look for: “If you want to request information about your financial standing, look for the phrase 'statutory report' on the CRAs' websites. You don't need to pay a fee for obtaining a statutory report.” Equifax publishes “You are entitled to receive a free statutory credit report for life, which details the full credit history Equifax holds on your file.” TransUnion publishes “You can request a free copy of your report to be sent by post.” The £2 is real, and it is in section 158(1) of the Consumer Credit Act 1974, which charges “a fee of £2”. But 158(4A) attaches a definition to it: “(a) a partnership consisting of two or three persons not all of whom are bodies corporate; or (b) an unincorporated body of persons which does not consist entirely of bodies corporate and is not a partnership”. The £2 in the Act is real and it is not yours to pay. Section 158 defines the word consumer, for that section alone, as a small partnership or an unincorporated body, so an individual asking for their own file falls outside the fee entirely. This is the correction that matters most, because the reader it misled is by definition the one who could least afford it.
Telling readers a broadband order is a soft search
What this page said
The page said “Most major UK broadband retailers run a soft search ... rather than a hard search at the order stage”, repeated it as a practical takeaway, and published a table giving thirteen named providers a check type, of which ten were labelled soft search typically.
What it says now, and why
Four of those providers publish the opposite about themselves. TalkTalk: “As part of our standard business policy, we always carry out a full credit check on all TalkTalk orders.” And “Once Equifax run the credit check, you'll see a credit search from TalkTalk on your credit file.” Virgin Media: “The agencies will record details of the search, whether or not the application goes ahead.” Vodafone: “When we run a credit check, the agencies will make a record of it on your credit file - known as a 'search footprint'. This may be seen by other lenders.” BT: “When credit reference agencies receive a search from us, a 'footprint' goes on your file which other organisations might see when they carry out a credit check.” Experian’s own list of what involves a hard check includes “You apply to a utility company”, and the phrase utility company appears nowhere on the page we replaced. Two of the thirteen rows were also stated without a published source of any kind: Plusnet publishes nothing about credit checks. Its privacy policy, its residential terms and its other things to know page contain no mention of a credit check, a credit search, a credit reference agency or a footprint. Sky's credit file help page loads its wording after the page arrives, so we could not read it. We quote nothing for Sky rather than guess, and that is different from Sky publishing nothing.
Sending readers to a regulator with no power over their provider
What this page said
The page named the Financial Conduct Authority eighteen times, said four times that a broadband contract is “regulated credit”, built an entire section on affordability assessment “as a regulatory requirement, not purely as a commercial choice”, and directed readers with credit file disputes to the Financial Ombudsman Service.
What it says now, and why
The FCA’s own list of the activities it authorises firms for has ten entries: Consumer credit activities; Benchmark-related regulated activities; Designated investment business; Electronic money; Funeral plan contracts; Insurance business; Insurance mediation; Operating a dormant account fund; The Lloyd's Market; Regulated home finance. Telecoms is in none of them. Its Consumer Duty guidance is explicit about reach: “The Duty applies to the regulated activities and ancillary activities of all firms authorised under the Financial Services and Markets Act 2000 (FSMA), the Payment Services Regulations 2017 (PSRs) and E-money Regulations 2011 (EMRs), in respect of products and services for prospective and actual retail customers.” A broadband retailer is authorised under none of those three. Affordability is not one of the four outcomes either, which are the governance of products and services; price and value; consumer understanding; consumer support. Broadband is Ofcom's, not the FCA's. If a provider has treated you badly over a credit decision, the route is the provider's own complaints process and then one of two free schemes, not the Financial Ombudsman. What the page should have published instead is the route that works: “Ofcom currently approves two ADR schemes: the Communication & Internet Services Adjudication Scheme (CISAS) and Communications Ombudsman.”, available “at least six weeks” after you complain.
Citing an Ofcom fine as an affordability case
What this page said
The page cited the Virgin Media penalty twice as “a relevant enforcement example” for affordability and credit assessment, and described it as being “for failures around vulnerable customer migration during cable network changes”.
What it says now, and why
The fine was about telecare customers during the move from analogue to digital landlines. Ofcom found Virgin Media failed properly to identify and record the status of telecare customers, and disconnected telecare customers who did not engage in the migration process. The word cable appears nowhere in the decision, and neither do credit checks, affordability or the FCA. Ofcom’s headline is “Ofcom fines Virgin Media £23.8 million for putting vulnerable customers at risk of harm”, and the condition breached requires a provider to “establish, publish and comply with clear and effective policies and procedures for the fair and appropriate treatment of consumers whose circumstances may make them vulnerable”. It is a real and serious case and it is about something else entirely. The genuine point underneath it survives and is now made properly: Ofcom’s rules on vulnerable customers do bind your provider. General Conditions C5.1 to C5.5 have been in force since October 2018, “requiring providers to have policies and procedures in place to make sure vulnerable customers are treated fairly”, and the definition is broad enough to cover most readers of this page: “Anybody can face circumstances that lead to them becoming vulnerable - temporarily or permanently. This might include physical or mental health problems, specific characteristics such as age or literacy skills, or changes in personal circumstances such as bereavement, job loss or changes in household income.” One honest limit goes with it: Ofcom's vulnerable customers guide does not mention credit checks, credit searches or affordability anywhere. The protection is about how you are treated, not about whether you pass a search.
Naming the ombudsman five times without the one detail that makes it usable
What this page said
The page mentioned the Communications Ombudsman and CISAS in five separate places, gave their web addresses, and explained that both are free. It never said how long you have to wait before you can use them.
What it says now, and why
“at least six weeks” after you first complain, or sooner if the provider gives you a deadlock letter. Without that, a reader either goes too early and is turned away, or assumes the route is theoretical and never goes at all. It is one clause and it is the difference between a signpost and a route. This is the smallest of the five corrections and it is the one most likely to have quietly cost somebody an outcome they were entitled to.
Credit checks and broadband: frequently asked questions
Is there really such a thing as no credit check broadband?
Yes, but it is a shorter list than the phrase suggests, and the honest version is that it is about how you pay rather than about which company you pick. Where you pay upfront there is nothing owed and so nothing to assess. Smarty puts the mechanism in one line: “We believe anyone should be entitled to mobile with no credit check. Because you pay upfront, we don't need to know your credit history.” giffgaff publishes the same for its SIM plans, “in most cases, we won't be doing any credit checks”, with the one caveat worth remembering: “We'll only carry out a credit check if you buy a phone on a contract with a loan.” The other genuinely searchless route is not a product at all, it is a position: if you already pay a provider for something and it offers a social tariff, BT publishes that “If you're an existing BT customer switching to Home Essentials, we won't carry out a credit check.” Everything else on the market runs something.
Do broadband providers run a soft search or a hard search?
A hard one, on the evidence the providers publish about themselves, which is the opposite of what most guides say including the version of this one we have just replaced. Experian's own list of what involves a hard check includes “You apply to a utility company”, beside “You apply for a loan, credit card or mortgage” and “You apply for a pay-monthly mobile phone contract”. TalkTalk says it outright: “As part of our standard business policy, we always carry out a full credit check on all TalkTalk orders.” And “Once Equifax run the credit check, you'll see a credit search from TalkTalk on your credit file.” A search you can see on your own file is by definition one other lenders can see. Vodafone describes it without using the word: “When we run a credit check, the agencies will make a record of it on your credit file - known as a 'search footprint'. This may be seen by other lenders.” BT publishes the same thing: “When credit reference agencies receive a search from us, a 'footprint' goes on your file which other organisations might see when they carry out a credit check.” None of the four describes a soft search anywhere.
Does a refused application still show on my credit file?
Yes, and this is the single most useful sentence any UK provider publishes on the subject. Virgin Media's own credit checking policy says: “The agencies will record details of the search, whether or not the application goes ahead.” The search is the record, not the outcome, so a decline leaves the same footprint an acceptance would. That is the whole argument for applying once rather than working down a list: three applications can leave three marks and connect you no faster than one. It is also why reading your own file first is worth the twenty minutes, because it is free, it leaves nothing, and it tells you what the provider is about to see.
How much does a statutory credit report cost?
Nothing, at any of the three agencies, and this page publishes that as a correction to its own previous version. The Information Commissioner's Office says: “You have the right to request a copy of the information held about your financial standing from any of the CRAs. Making this request is free of charge.” It also tells you what to look for: “If you want to request information about your financial standing, look for the phrase 'statutory report' on the CRAs' websites. You don't need to pay a fee for obtaining a statutory report.” Equifax publishes “You are entitled to receive a free statutory credit report for life, which details the full credit history Equifax holds on your file.” TransUnion publishes “You can request a free copy of your report to be sent by post.” The £2 that every guide cites is real and it is in section 158(1) of the Consumer Credit Act 1974, which charges “a fee of £2”. Read on to 158(4A) and there is a definition attached to it: “(a) a partnership consisting of two or three persons not all of whom are bodies corporate; or (b) an unincorporated body of persons which does not consist entirely of bodies corporate and is not a partnership”. The £2 in the Act is real and it is not yours to pay. Section 158 defines the word consumer, for that section alone, as a small partnership or an unincorporated body, so an individual asking for their own file falls outside the fee entirely.
How long does a hard search stay on my file?
“Most hard searches will stay on your credit report for 12 months.” Experian's own wording, and EE says the same from the provider side: “When you apply for a contract with us, the credit search will remain on file for 12 months. After this, it's automatically removed from your credit file.” So a difficult few months is not permanent, and a plan that involves waiting is a real plan rather than a fob-off. There is a second half to this that is more encouraging and that almost nobody mentions: EE also publishes “We make a record of how you conduct your account. This information is provided to the agencies automatically each month.” A broadband account paid on time reports to the agencies every month, which makes it one of the cheapest ways there is to put something good on a thin file.
Does the FCA regulate broadband contracts?
No. The FCA's own list of the activities it authorises firms for runs to ten entries: Consumer credit activities; Benchmark-related regulated activities; Designated investment business; Electronic money; Funeral plan contracts; Insurance business; Insurance mediation; Operating a dormant account fund; The Lloyd's Market; Regulated home finance. Telecoms is in none of them. Its Consumer Duty guidance is explicit about reach: “The Duty applies to the regulated activities and ancillary activities of all firms authorised under the Financial Services and Markets Act 2000 (FSMA), the Payment Services Regulations 2017 (PSRs) and E-money Regulations 2011 (EMRs), in respect of products and services for prospective and actual retail customers.” A broadband retailer is authorised under none of those three, so the Duty does not apply to it. Affordability is not one of the Duty's four outcomes either, which are the governance of products and services; price and value; consumer understanding; consumer support. Broadband is Ofcom's, not the FCA's. If a provider has treated you badly over a credit decision, the route is the provider's own complaints process and then one of two free schemes, not the Financial Ombudsman. The one place the FCA does come near this is hardware paid off monthly: “DPC is an interest-free form of credit, repayable in 12 or fewer instalments, over 12 months or less.” And even there, “If you buy something from a business and use DPC that's provided by that same business, it will not be regulated.”
Where do I complain if a provider has treated me badly over a credit decision?
To the provider first, and then to one of two free schemes. “Ofcom currently approves two ADR schemes: the Communication & Internet Services Adjudication Scheme (CISAS) and Communications Ombudsman.” You may go to one “at least six weeks” after you complain, or sooner if the provider gives you a deadlock letter. Ofcom's rules are the ones that bind your provider here. General Conditions C5.1 to C5.5 have been in force since October 2018, “requiring providers to have policies and procedures in place to make sure vulnerable customers are treated fairly”, and the definition of vulnerable is wider than people expect. “Anybody can face circumstances that lead to them becoming vulnerable - temporarily or permanently. This might include physical or mental health problems, specific characteristics such as age or literacy skills, or changes in personal circumstances such as bereavement, job loss or changes in household income.” The phrase changes in household income covers most people reading this page. One honest caveat: Ofcom's vulnerable customers guide does not mention credit checks, credit searches or affordability anywhere. The protection is about how you are treated, not about whether you pass a search.
I am on Universal Credit. Does a social tariff skip the credit check?
Sometimes, and it depends on whether you are already the provider's customer rather than on the tariff. BT publishes both halves on one page: “If you're new to BT, we'll carry out a credit check as part of your application.” And “If you're an existing BT customer switching to Home Essentials, we won't carry out a credit check.” So the same tariff, from the same company, costs you a search or nothing depending on which of the two you are when you ask. Ofcom adds that “If your provider offers a social tariff, you can switch to it at any time, free of charge.” and that “It costs nothing to leave. You won't pay a fee to leave the tariff before the end of your contract.” Ofcom's social tariffs page does not contain the words credit check or credit search anywhere. Whether a search runs is the provider's choice, not part of the scheme. Our UK social tariffs guide covers who qualifies and what each one costs.
Will buying a router or a hub on monthly payments affect this?
Yes, and it is the one part of a broadband order that is credit in the ordinary sense. giffgaff draws the line precisely: “We'll only carry out a credit check if you buy a phone on a contract with a loan.” Buy the hardware outright and the route stays clean; pay it off monthly and a search comes with it. There is a second reason to ask who the lender is. The FCA describes deferred payment credit as “DPC is an interest-free form of credit, repayable in 12 or fewer instalments, over 12 months or less.”, and then adds “If you buy something from a business and use DPC that's provided by that same business, it will not be regulated.” So a provider spreading the cost of its own hub is outside FCA regulation, while a third party lender in the middle is inside it. That changes which protections you have, and neither arrangement announces itself at the checkout.
Which credit reference agency will the provider use?
It depends on the provider, and it matters more than people expect: Experian, Equifax and TransUnion do not hold the same file. An entry that sinks an application at one company may not exist at the agency the next one uses. TalkTalk names its own outright: “Credit checks are carried out on our behalf by Equifax, an independent credit agency.” Vodafone and EE both name all three. BT names none in its privacy policy, describing agencies in the plural instead. So the practical move is to read your file at all three rather than at whichever one a free service happens to use, and after a refusal to ask which one was searched. That is an ordinary customer service question and the answer tells you where to look.
Can I get broadband while I am in an IVA, a DRO or a debt management plan?
Almost certainly yes, and the honest caveat is that we cannot tell you which providers will say yes, because none of them publishes a policy on it. Not one of the nine companies checked for this page mentions bankruptcy, an individual voluntary arrangement, a debt relief order or a debt management plan anywhere. Guides that list the accommodating ones are describing something no provider has written down. What is published is the structure, and the structure is what helps. A prepaid route involves no assessment at all, because “We believe anyone should be entitled to mobile with no credit check. Because you pay upfront, we don't need to know your credit history.” A social tariff turns on a qualifying benefit rather than on your file. And if you are already a provider's customer, BT at least publishes that “If you're an existing BT customer switching to Home Essentials, we won't carry out a credit check.”
Is a rolling monthly contract easier to get than a two year one?
It sounds as though it should be and nothing published supports it. TalkTalk says “As part of our standard business policy, we always carry out a full credit check on all TalkTalk orders.”, with no tier and no term attached. Virgin Media reserves its position completely: “We are entitled to carry out a credit check on you at any time.” Neither publishes a lower bar for a shorter commitment, and nor does anybody else. So this page will not tell you a rolling plan gets you through where a longer one would not. What does remove the question is paying upfront, because then there is no contract for anybody to assess: “No minimum term contract, the freedom to cancel at any time, and the flexibility to add more data whenever you need it.” That is the difference between a shorter commitment and no commitment, and only one of the two is published as changing the answer.
What is the single most useful thing I can do?
Check your own file first, because looking at it yourself leaves no mark, and then make one application rather than three. Reading your own file is the only step here that is free, invisible to everybody else and useful whatever you decide afterwards, and it is the step the guide this page replaces charged about £6 for. “You have the right to request a copy of the information held about your financial standing from any of the CRAs. Making this request is free of charge.” Then make one application, to the provider you have actually decided on, because “The agencies will record details of the search, whether or not the application goes ahead.”
In short
- Almost every broadband order runs a hard credit search, the providers say so themselves, and the search is recorded whether or not you are accepted. So the question worth asking is not who will let you in, it is what order to do things in so that fewer searches happen at all.
- What a soft search is: “Soft searches aren't visible to companies”, so “they have no impact on your credit score or any future credit applications”
- And a hard one: “A hard credit check happens when a company makes a complete search of your credit report. Each hard check is recorded on your report.”
- How long it stays: “Most hard searches will stay on your credit report for 12 months.”
- Broadband is on Experian's hard list: “You apply to a utility company”
- Beside “You apply for a loan, credit card or mortgage” and “You apply for a pay-monthly mobile phone contract”
- TalkTalk: “As part of our standard business policy, we always carry out a full credit check on all TalkTalk orders.” “Credit checks are carried out on our behalf by Equifax, an independent credit agency.” “Once Equifax run the credit check, you'll see a credit search from TalkTalk on your credit file.”
- Virgin Media: “We are entitled to carry out a credit check on you at any time.”
- And the sentence that matters most: “The agencies will record details of the search, whether or not the application goes ahead.”
- What it may do instead of refusing: “Demand a deposit from you.”
- Vodafone: “When we run a credit check, the agencies will make a record of it on your credit file - known as a 'search footprint'. This may be seen by other lenders.”
- BT: “When credit reference agencies receive a search from us, a 'footprint' goes on your file which other organisations might see when they carry out a credit check.”
- EE: “When you apply for a contract with us, the credit search will remain on file for 12 months. After this, it's automatically removed from your credit file.”
- And the encouraging half: “We make a record of how you conduct your account. This information is provided to the agencies automatically each month.”
- Plusnet publishes nothing about credit checks. Its privacy policy, its residential terms and its other things to know page contain no mention of a credit check, a credit search, a credit reference agency or a footprint.
- Sky's credit file help page loads its wording after the page arrives, so we could not read it. We quote nothing for Sky rather than guess, and that is different from Sky publishing nothing.
- The order changes the answer. BT: “If you're new to BT, we'll carry out a credit check as part of your application.”
- And: “If you're an existing BT customer switching to Home Essentials, we won't carry out a credit check.”
- Ofcom on social tariffs: “If your provider offers a social tariff, you can switch to it at any time, free of charge.” “It costs nothing to leave. You won't pay a fee to leave the tariff before the end of your contract.”
- Ofcom's social tariffs page does not contain the words credit check or credit search anywhere. Whether a search runs is the provider's choice, not part of the scheme.
- Paying upfront: “We believe anyone should be entitled to mobile with no credit check. Because you pay upfront, we don't need to know your credit history.”
- With no term: “No minimum term contract, the freedom to cancel at any time, and the flexibility to add more data whenever you need it.”
- giffgaff on SIM plans: “in most cases, we won't be doing any credit checks”
- And the trigger that brings the search back: “We'll only carry out a credit check if you buy a phone on a contract with a loan.”
- A prepaid SIM avoids the search because nothing is owed. Add hardware paid off monthly and the loan comes back, and so does the search.
- The report is free: “You have the right to request a copy of the information held about your financial standing from any of the CRAs. Making this request is free of charge.”
- What to look for: “If you want to request information about your financial standing, look for the phrase 'statutory report' on the CRAs' websites. You don't need to pay a fee for obtaining a statutory report.”
- Equifax: “You are entitled to receive a free statutory credit report for life, which details the full credit history Equifax holds on your file.”
- TransUnion: “You can request a free copy of your report to be sent by post.”
- The fee in the Act: section 158(1)(c) charges “a fee of £2”
- And who it is for: “(a) a partnership consisting of two or three persons not all of whom are bodies corporate; or (b) an unincorporated body of persons which does not consist entirely of bodies corporate and is not a partnership”
- The £2 in the Act is real and it is not yours to pay. Section 158 defines the word consumer, for that section alone, as a small partnership or an unincorporated body, so an individual asking for their own file falls outside the fee entirely.
- How long a correction takes: “Unless the CRA needs more information, they have one month from receiving your request to respond. In certain circumstances they may need extra time to consider your request and can take up to an extra two months.”
- And where to send it: “raise your complaints with the relevant CRA you obtained your file from. However, the problem may lie with the original lender or organisation that supplied the CRA with the information so you will need to contact them instead.”
- The FCA's own list: Consumer credit activities; Benchmark-related regulated activities; Designated investment business; Electronic money; Funeral plan contracts; Insurance business; Insurance mediation; Operating a dormant account fund; The Lloyd's Market; Regulated home finance
- The Duty's reach: “The Duty applies to the regulated activities and ancillary activities of all firms authorised under the Financial Services and Markets Act 2000 (FSMA), the Payment Services Regulations 2017 (PSRs) and E-money Regulations 2011 (EMRs), in respect of products and services for prospective and actual retail customers.”
- Its four outcomes, and affordability is not among them: the governance of products and services; price and value; consumer understanding; consumer support
- Hardware credit: “DPC is an interest-free form of credit, repayable in 12 or fewer instalments, over 12 months or less.”
- And when it is not regulated: “If you buy something from a business and use DPC that's provided by that same business, it will not be regulated.”
- Broadband is Ofcom's, not the FCA's. If a provider has treated you badly over a credit decision, the route is the provider's own complaints process and then one of two free schemes, not the Financial Ombudsman.
- The two schemes: “Ofcom currently approves two ADR schemes: the Communication & Internet Services Adjudication Scheme (CISAS) and Communications Ombudsman.”
- After “at least six weeks”
- Ofcom's General Conditions C5.1 to C5.5, in force since October 2018, “requiring providers to have policies and procedures in place to make sure vulnerable customers are treated fairly”
- Who that covers: “Anybody can face circumstances that lead to them becoming vulnerable - temporarily or permanently. This might include physical or mental health problems, specific characteristics such as age or literacy skills, or changes in personal circumstances such as bereavement, job loss or changes in household income.”
- Ofcom's vulnerable customers guide does not mention credit checks, credit searches or affordability anywhere. The protection is about how you are treated, not about whether you pass a search.
- The fine was about telecare customers during the move from analogue to digital landlines. Ofcom found Virgin Media failed properly to identify and record the status of telecare customers, and disconnected telecare customers who did not engage in the migration process. The word cable appears nowhere in the decision, and neither do credit checks, affordability or the FCA.
- Check your own file first, because looking at it yourself leaves no mark, and then make one application rather than three.
Each line stands on its own and carries its date. Reviewed by a person at least quarterly, last on .
References
- ICO
Information Commissioner’s Office. Credit, last updated 8 July 2026. The right to request the information a credit reference agency holds about your financial standing, the statement that the request is free of charge, the phrase statutory report, the one month response period and the extension to three, and where to take a dispute when the data came from a lender rather than from the agency. Read 30 September 2026. ico.org.uk
- legislation.gov.uk
Consumer Credit Act 1974, section 158, as amended. Subsection (1)(c) for the £2 fee that every guide cites, and subsection (4A) for the definition of consumer that applies to that section, which covers small partnerships and unincorporated bodies and does not cover an individual. Read 30 September 2026. legislation.gov.uk
- Equifax and TransUnion
Equifax. Statutory Credit Report, no date shown, for the free statutory report for life. TransUnion. What is a statutory credit report?, no date shown, for the free copy by post and the routes to request one. Both read 30 September 2026. equifax.co.uk
- Experian
Experian. What is a credit check? Hard and soft credit checks, no date shown. The definition of a soft search and the statement that it is not visible to companies, the definition of a hard check and that each is recorded, the twelve month retention, and the list of what involves a hard check, which includes applying to a utility company. Read 30 September 2026. experian.co.uk
- TalkTalk
TalkTalk. Joining TalkTalk, help centre article, last modified 3 September 2025. That a full credit check is carried out on all TalkTalk orders as standard business policy, that Equifax carries them out, and that the customer will see the search on their own credit file. Read 30 September 2026. talktalk.co.uk
- Virgin Media
Virgin Media. Credit Checking Policy, no date shown. That it is entitled to carry out a credit check at any time, that the agencies record details of the search whether or not the application goes ahead, and the three things it may do where a check is not satisfactory: demand payment for future line rental and usage charges, enforce credit limits and suspend services, and demand a deposit. Read 30 September 2026. virginmedia.com
- Vodafone, BT and EE
Vodafone. Credit checks explained, no date shown, for the search footprint that other lenders may see and the three agencies it uses. BT. Privacy policy, no date shown, for the footprint that other organisations might see. EE. Credit files explained, no date shown, for the twelve month retention and the monthly reporting of account conduct. All read 30 September 2026. vodafone.co.uk
- Plusnet and Sky
Plusnet. Privacy policy, its residential terms and its other things to know page, searched for credit check, credit search, credit reference agency and footprint. None appears, which is recorded here as a silence rather than as a policy. Sky. Your credit file, which returns its headings and loads its body text after the page arrives, so nothing is quoted for Sky. Both read 30 September 2026. plus.net
- BT
BT. Home Essentials, no date shown. That a customer new to BT gets a credit check as part of the application and an existing BT customer switching to Home Essentials does not, the £16.50 headline price, the twelve month contract and the absence of early exit fees. Read 30 September 2026. bt.com
- Ofcom
Ofcom. Social tariffs: cheaper broadband and phone packages, last updated 17 August 2026. That you can switch to a social tariff at any time free of charge and that it costs nothing to leave before the end of the contract. Searched for credit check and credit search, neither of which appears anywhere on the page. Read 30 September 2026. ofcom.org.uk
- Smarty and giffgaff
SMARTY. No credit check SIM only deals, no date shown, for the statement that because you pay upfront it does not need to know your credit history, the absence of a minimum term, and that SMARTY is a trading name of Hutchison 3G UK Limited. giffgaff. Will there be any credit checks with contracts or phones bought with giffgaff?, no date shown, for the statement that in most cases no credit check is run and that one is carried out only where a phone is bought on a contract with a loan. Both read 30 September 2026. smarty.co.uk
- FCA
Financial Conduct Authority. Activities we regulate, no date shown, for the ten categories of regulated activity, none of which is telecoms. FG22/5: Final non-Handbook Guidance for firms on the Consumer Duty, published July 2022, paragraph 2.1 for the firms the Duty applies to and paragraph 1.3 for the four outcomes. Buy now pay later, published 11 February 2026 and last updated 27 April 2026, for the definition of deferred payment credit and for when it is and is not regulated. All read 30 September 2026. fca.org.uk
- Ofcom
Ofcom. Making a complaint and using ADR schemes, last updated 6 August 2026, for the two approved schemes and the six week waiting period. Treating vulnerable customers fairly: a guide for phone, broadband and pay-TV providers, published 25 September 2019 and last updated 29 September 2022, for General Conditions C5.1 to C5.5 and the breadth of the definition. Searched for credit check, credit search and affordability, none of which appears. Read 30 September 2026. ofcom.org.uk
- Ofcom
Ofcom. Ofcom fines Virgin Media £23.8 million for putting vulnerable customers at risk of harm, published 1 December 2025. The breach of General Condition C5.2, the finding that Virgin Media failed properly to identify and record the status of telecare customers and disconnected those who did not engage, and the migration from analogue to digital landlines that the case concerns. Searched for cable, credit check, affordability and FCA, none of which appears. Read 30 September 2026. ofcom.org.uk
Ready to see what reaches your address?
One postcode shows every provider that reaches it, lowest price first. Decide which one you want before you apply, because the search lands whether or not they say yes.
Compare at this postcode →